Average Rv Loan Length

There’s something genuinely enjoyable about planning for an RV. You get to dream about open highways, campfire coffee, and the freedom to park your home in a stunning new loca...
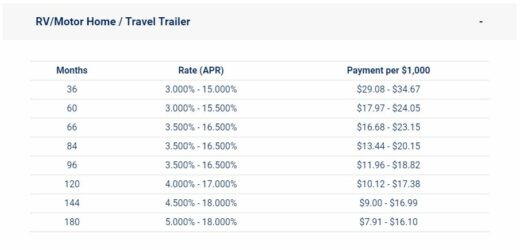
There’s something genuinely enjoyable about planning for an RV. You get to dream about open highways, campfire coffee, and the freedom to park your home in a stunning new location every few days. But before you can hit the road, there’s a practical piece of the puzzle that deserves a little love: figuring out the average RV loan length. It’s a topic that feels a bit like choosing the right sleeping bag—not the most glamorous, but absolutely essential for a comfortable trip. The main purpose of understanding loan terms is to align your monthly budget with your lifestyle, ensuring you can enjoy the journey without financial stress. For retirees, a shorter loan might mean owning the rig before their fixed income shrinks; for younger families, a longer term can keep payments low, freeing up cash for campground fees and gas.
You’ve probably noticed the two most common variations: the 10-year loan and the 15- to 20-year loan. A 10-year term is popular for used RVs, where monthly payments are higher but interest costs are much lower. On the flip side, a 20-year term is typical for a brand-new, luxury motorhome, keeping payments manageable but often adding thousands in total interest. Think of it like renting an apartment versus buying a house—one is faster and cheaper in the long run, the other gives you more breathing room month to month.
The real trick is matching the loan length to how you actually use the RV. If you’re planning to travel full-time for three years and then sell, a shorter loan makes sense so you build equity quickly. But if you plan on weekend getaways for the next decade, a longer term lets you invest the savings in maintenance and upgrades. Remember, an RV depreciates fast, so you don’t want to owe more than it’s worth when you’re ready to trade up.
Must Read
To get started, run the numbers on a simple calculator. Aim for a monthly payment that is no more than 10% of your take-home pay. If the 10-year loan pushes you over that limit, don’t panic—just stretch the term to 15 years. This trade-off is common and often the most practical way to own an RV without overextending yourself.
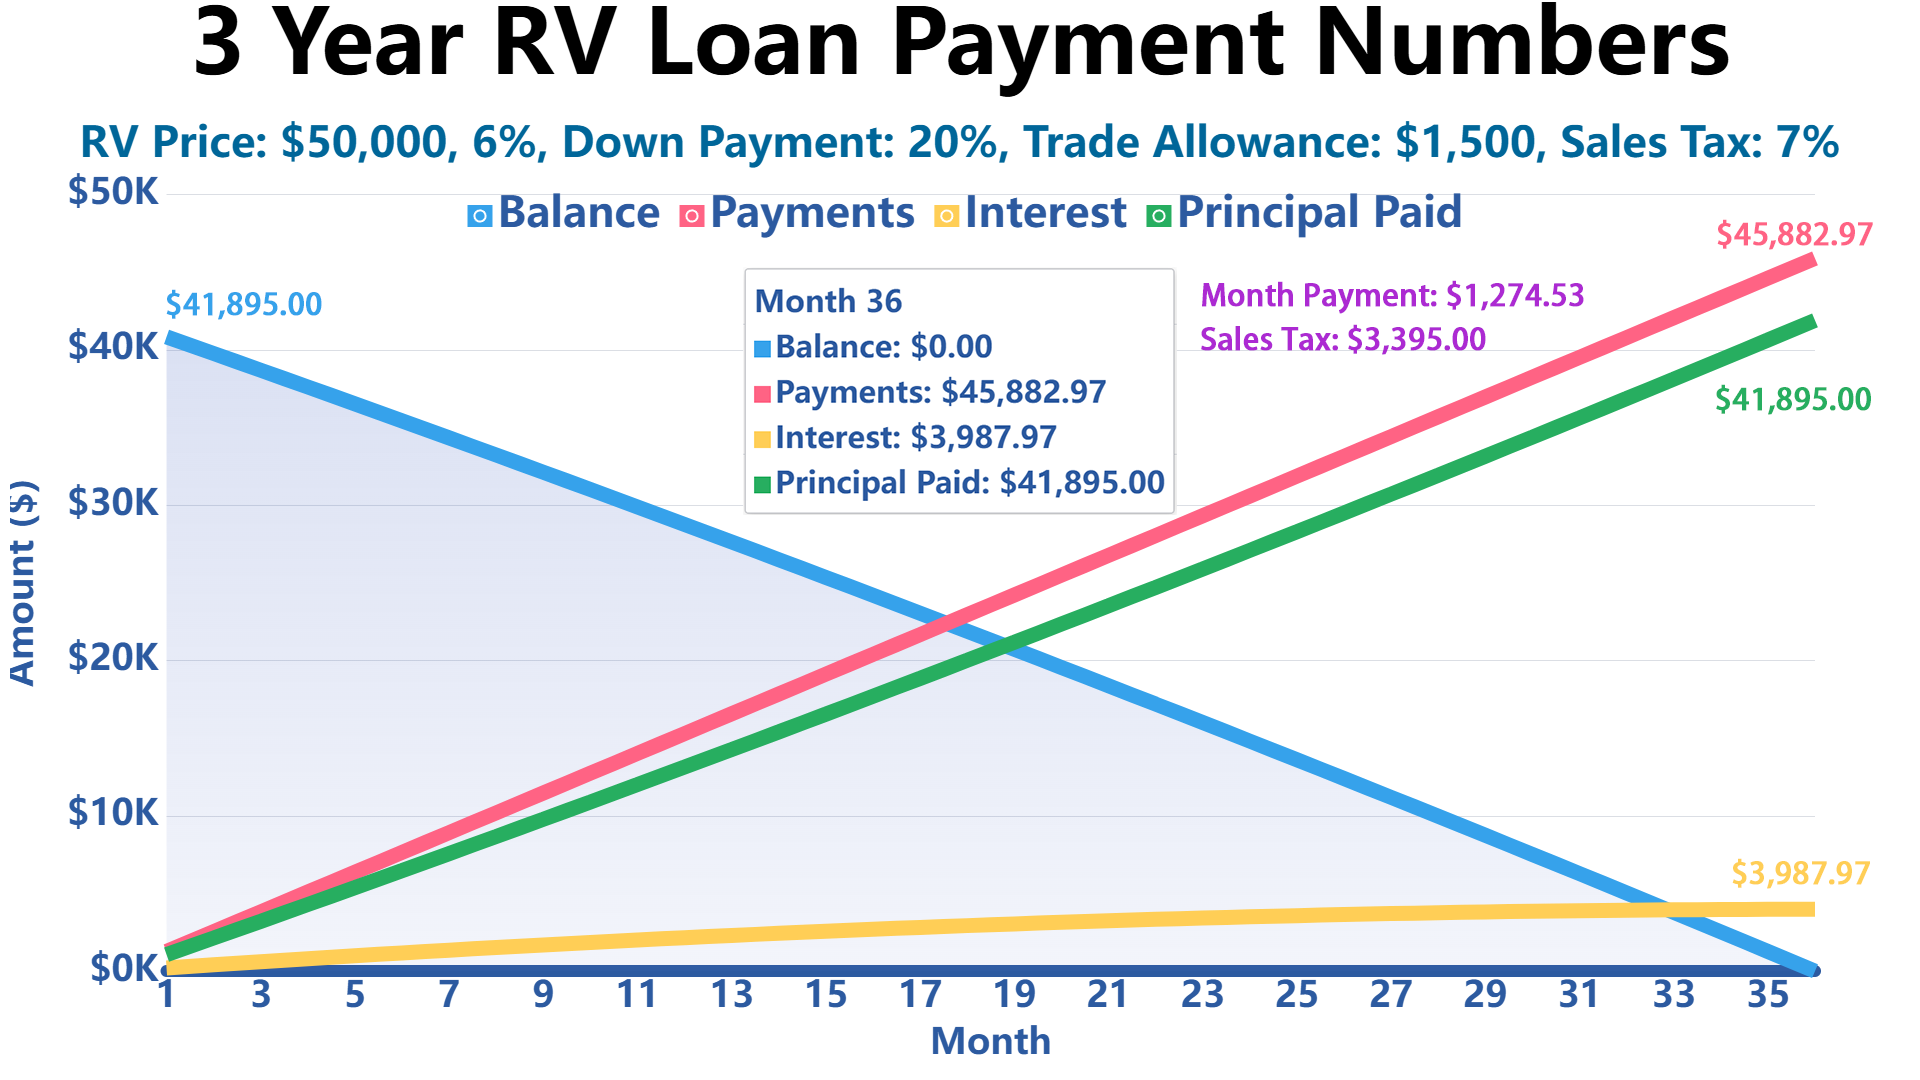 RV Loan Calculator | MoneyCalc
Another actionable tip: put at least 20% down. A bigger down payment reduces the loan amount and can even help you qualify for a lower interest rate. Plus, it gives you instant positive equity, so you’re never underwater if life throws a curveball and you need to sell.
Finally, don’t forget to shop around for rates. Credit unions and RV-specific lenders often offer better terms than big banks. A difference of just 1% in rate on a 20-year loan can save you thousands of dollars over the life of the loan. So take your time, play with the numbers, and pick the term that feels right for your adventure.

