Can You Finance A Used Rv

Picture this: the open road, a cozy home-on-wheels, and the freedom to chase sunsets wherever they lead. That’s the dream of owning an RV, and the best part? You don’t need a...
Picture this: the open road, a cozy home-on-wheels, and the freedom to chase sunsets wherever they lead. That’s the dream of owning an RV, and the best part? You don’t need a pile of cash to make it happen. Yes, you can absolutely finance a used RV, and it’s often the smartest way to start your adventure. Financing lets you spread the cost over time, keeping your savings intact for campground fees, repairs, or that big fuel stop in Montana.
The real magic of used RV financing is value. New RVs can drop in value faster than you can say “depreciation,” but a used rig has already taken that hit. You get a fully-equipped home for a fraction of the original price, and lenders are happily on board. Banks, credit unions, and even RV-specific lenders specialize in used loans, often with competitive rates. Just remember: the newer the used RV, the lower your interest rate might be—think 2018 model versus a 1998 beater.
Let’s paint a fun example: Meet Sarah and Mike, a couple who wanted a road trip rig but had only $5,000 saved. They found a 2015 Class C motorhome for $35,000. By financing $30,000 over 10 years at 6% interest, their monthly payment came to roughly $333. That’s less than a weekend hotel stay, and they hit the road in six months. They used their savings for a new mattress and tires—smart budgeting, not a burden.
Must Read
Here’s a creative twist: consider “DIY” financing by buying a cheaper used RV from a private seller. Many sellers accept a personal loan from a bank—you pay them directly. Or, join a club like Good Sam or Escapees that offer member financing perks. Another idea? Use a recreational vehicle loan from a credit union—they often have lower rates for used rigs because they know the RV lifestyle retains loyalty.
 Best RV Loans of 2025: RV Finance Options
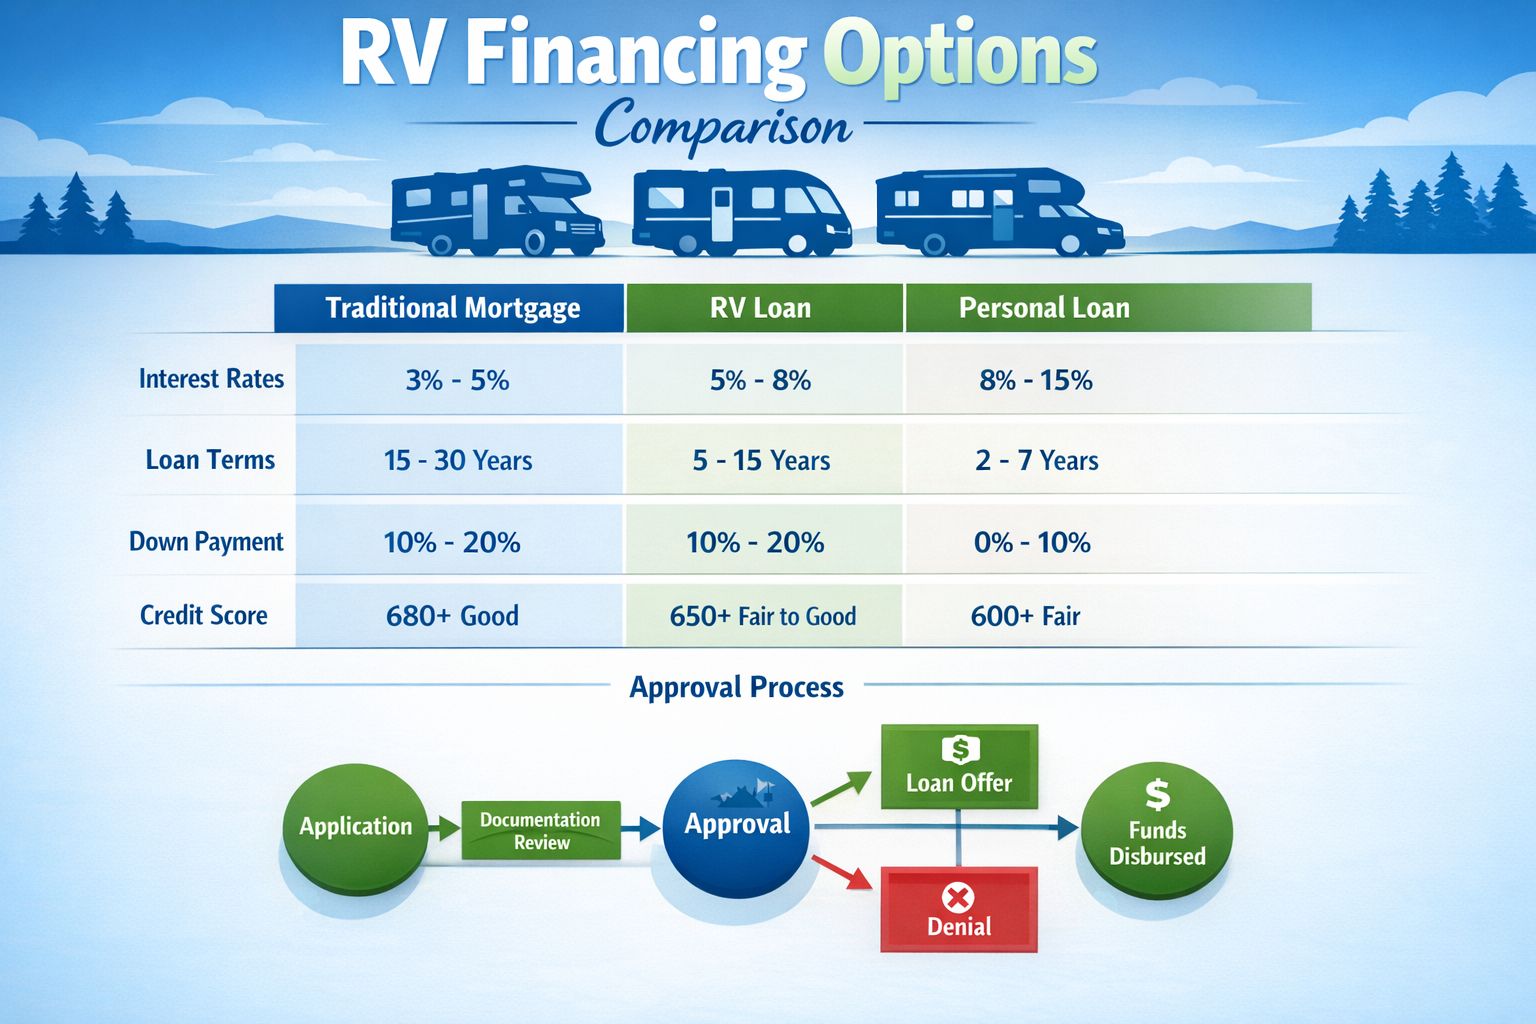
Practical advice for your financing journey: check your credit score first. A score above 700 unlocks the best rates, but many lenders accept 620–680 with slightly higher APR. Get pre-approved from at least three lenders to compare terms—don’t just accept the dealer’s first offer. Also, plan for a down payment of 10–20% to show you’re serious and to lower monthly payments.
Finally, inspect the RV before committing. Financing a lemon is worse than no RV at all. Hire a certified RV inspector (about $500–$800), and insist on a “clean title”—no salvage or flood damage. The lender will require this too, so it’s win-win. With solid planning, financing a used RV turns a dream into a drivable reality, and your only worry will be which scenic exit to take next.

