Choosing An Embedded Finance Partner For My Saas Business.

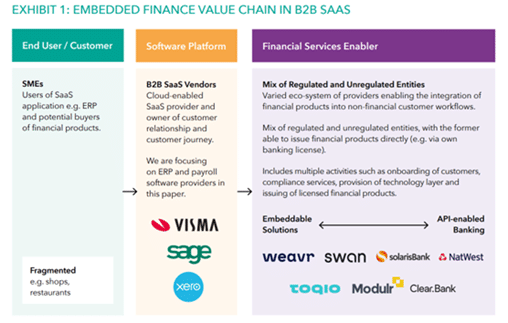
Welcome to the wonderfully wild world of embedded finance! If you run a SaaS business, you’ve probably dreamed of adding payments, lending, or banking features directly into y...
Welcome to the wonderfully wild world of embedded finance! If you run a SaaS business, you’ve probably dreamed of adding payments, lending, or banking features directly into your platform—without building a bank from scratch. This isn’t just a tech upgrade; it’s like giving your software a superpower. The purpose? To keep users glued to your product, boost your revenue, and turn a one-time subscription into a sticky, financial ecosystem. The advantage? You stop being a tool and start being a financial hub for your customers.
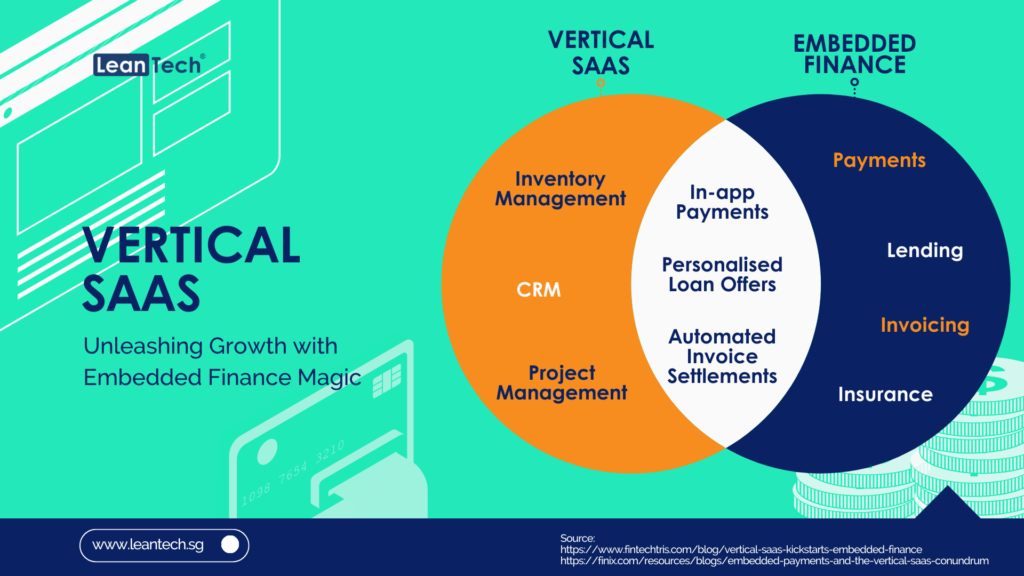
Imagine your accounting software offering instant invoice financing, or your project management tool letting clients pay contractors in one click. That’s the magic. For example, a fitness coaching SaaS could partner with a payments provider to let trainers accept monthly membership fees inside the app, with zero friction. Or a property management platform might embed escrow services, building trust while cutting out messy third-party apps. The creative twist here is that you don’t need to invent the wheel—you just need to choose a partner who wheels it for you.
But picking an embedded finance partner is like choosing a dance partner for a salsa competition: chemistry matters. First, check if they offer API-first integration—your dev team should be able to plug in features as easily as stacking LEGO bricks. Next, peek under the hood of their compliance. If they handle KYC, fraud checks, and regulatory reporting, you save months of headaches. A good partner will also provide sandbox environments so you can test wallet features or payment flows without real money slipping through the cracks.
Must Read
Now, for the secret sauce: diversification. Don’t just look at payment processing; consider partners offering virtual cards, savings accounts, or even white-label lending. For instance, a B2B SaaS for freelancers could embed a “Get Paid Now” button that advances invoices instantly. The partner’s balance sheet handles the risk; you handle the joy. Also, keep an eye on revenue sharing models. Some partners split interchange fees or loan interest, turning your feature into a profit center, not just a cost.
 AI Initiatives in GCC Countries: Transforming the Future - LeanTech SG
Here’s a pro tip: start small, then scale fast. Begin with a single feature—like embedded payments for your highest tier. Monitor user adoption and churn rates. If customers love it, add recurring billing or embedded insurance for your niche. Another tip: negotiate SLA guarantees. Uptime is crucial when money is involved; a partner with 99.99% uptime is worth more than a cheap one with frequent outages.
Finally, remember that the best partners act as consultants, not just vendors. Look for one that offers dedicated support during launch and ongoing optimization. They should explain their fee structures in plain English—no hidden “per transaction” surprises. When you find that partner, you’ll wonder how you ever ran a SaaS without the ability to move money right inside your software. So go ahead: dance with the right partner, and watch your platform become indispensable.