Chrysler Car Loan Rates

So, you’re thinking about buying a Chrysler. Maybe you’ve got your eye on a Pacifica, because nothing says “I’m an adult” like a minivan that can swallow a Costco run whole. B...
So, you’re thinking about buying a Chrysler. Maybe you’ve got your eye on a Pacifica, because nothing says “I’m an adult” like a minivan that can swallow a Costco run whole. But before you fall in love with that leather smell, we need to talk about the elephant in the showroom: car loan rates.
Let’s be honest: comparing Chrysler car loan rates is about as fun as watching paint dry. But not doing it is like showing up to a water balloon fight with a sieve. You’ll get soaked—financially.
The Teaser You Shouldn’t Trust
Chrysler loves to dangle a 0% APR offer in front of you like a shiny set of keys. It looks amazing, right? Surprising fact: That rate often only applies to a 36-month loan, which means your monthly payment could be higher than your rent.
Must Read
If you take that 0% deal, you’re basically agreeing to pay off the car faster than a kid eats a candy bar. That’s great for people with deep pockets, but for the rest of us? It’s a trap disguised as a bargain.
Why Your Credit Score Matters (A Lot)
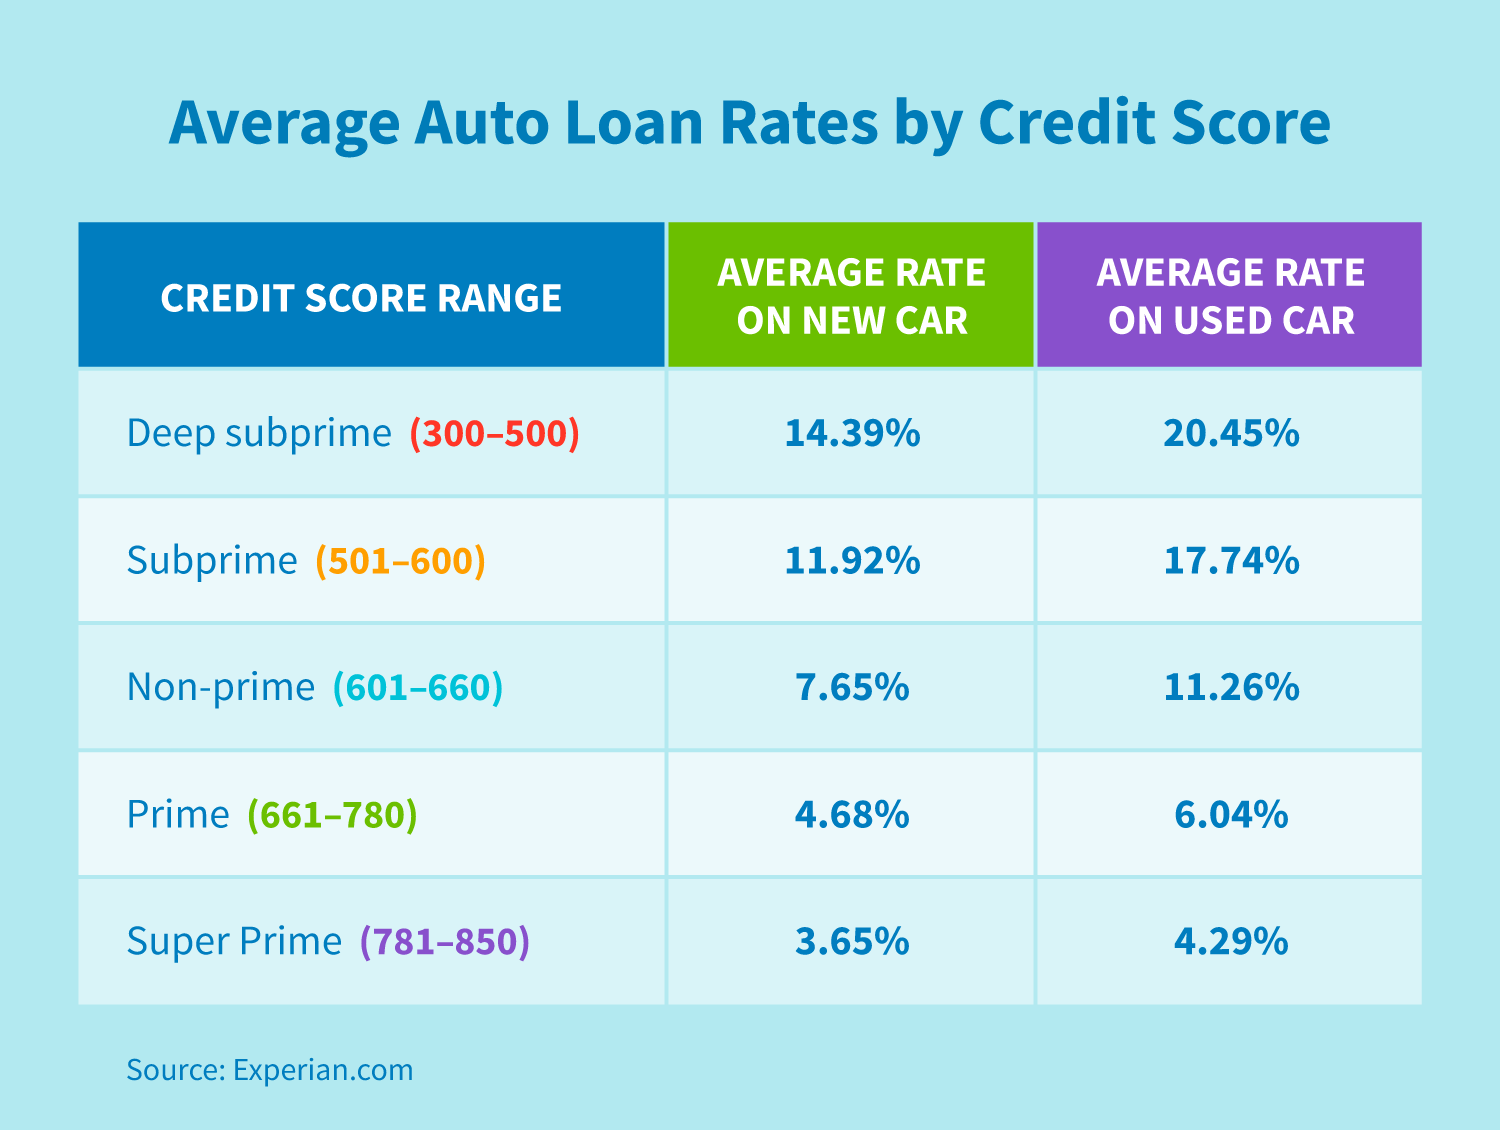
Your credit score is like your dating profile score for money. If it’s above 740, lenders swoon. They’ll offer you rates near 4% or 5%, which is practically free money in this economy.
If your score is lower, say in the 600s, Chrysler’s finance arm will look at you like you just brought a raccoon to a wedding. You’ll get rates closer to 10% or 12%, which turns a $35,000 car into a $50,000 nightmare. Ouch.
The Secret Dealers Don’t Tell You
Here’s a surprising fact that will save you money: Chrysler Capital sometimes offers better rates on last year’s models. You know, the ones that smell faintly of regret and have 50 miles on the odometer.
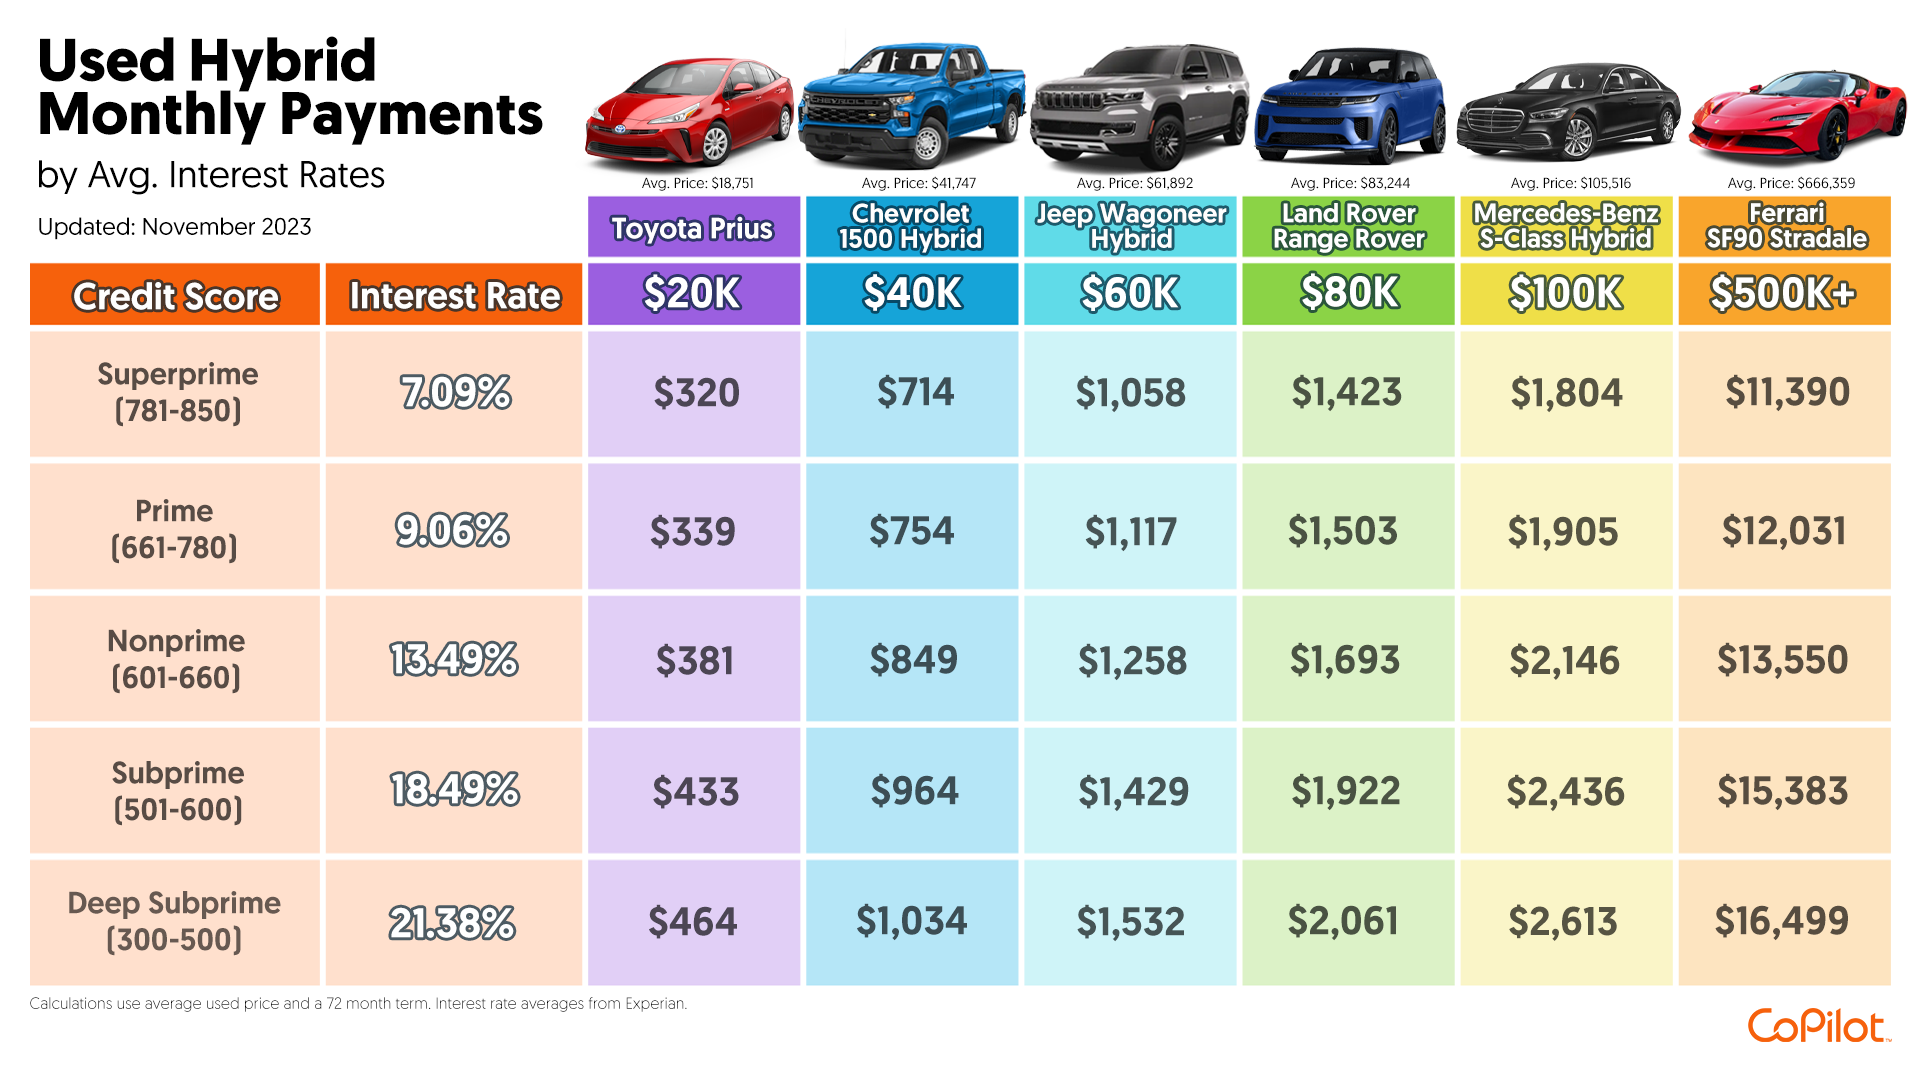 🚗4 charts that show how interest rates impact used car affordability
Don’t be too proud to buy a “used” new car. It’s like finding a twenty-dollar bill in a jacket you haven’t worn since winter. That savings could buy you a whole lot of car snacks.
Playing the Rate Game
You don’t have to take Chrysler’s first offer. That’s like accepting the first bid in a poker game—you’re gonna lose. Shop around. Your local credit union might give you a rate that makes Chrysler Capital blush.
I once got a rate of 2.9% from a credit union while Chrysler was offering 4.5%. The finance manager actually sighed when I showed him the check. That sigh was music to my ears.
Leasing vs. Buying: The Comedy Showdown
If you lease a Chrysler, you’re basically renting a car and giving it back like a video tape you forgot to rewind. The rates are usually lower, but you’ll never own a thing. Poof—your money disappears.
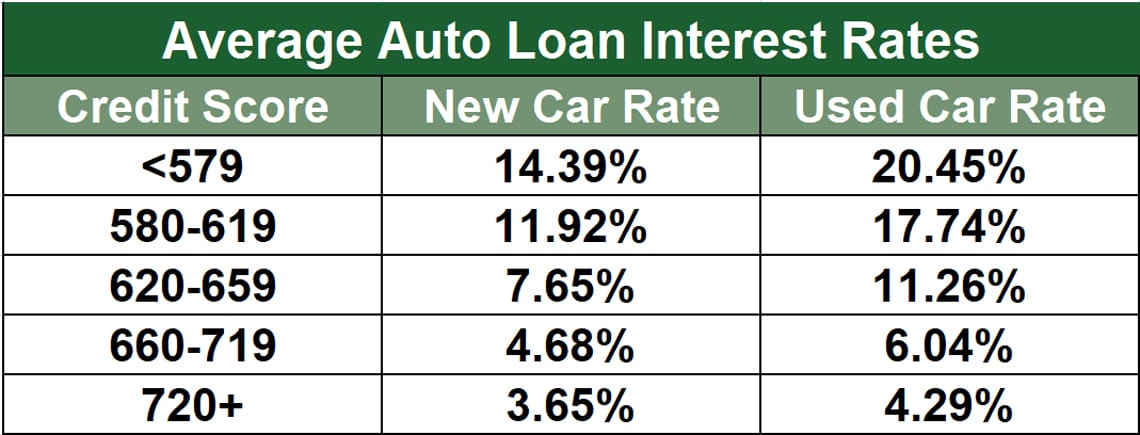 Credit Score Charts: Data & Trends - BadCredit.org
Buying with a loan feels more like a marriage. You make payments for five years, and then you’re stuck with a car that’s value has dropped faster than a hot potato. But hey, at least it’s your potato.
The Bottom Line (No Pun Intended)
Chrysler car loan rates are a jungle. You need a machete made of good credit and a map drawn with comparison shopping. Don’t be hypnotized by a low monthly payment—check the total cost.
And remember: if a deal sounds too good to be true, it probably involves a 72-month loan with a balloon payment. Run. Run like the car is on fire—because your wallet will be.
Now go forth, negotiate like your favorite uncle at a flea market, and drive off into the sunset with a rate that doesn’t make you cry. Or at least, not too hard.
