Consumer Credit Act Meaning

Imagine you’ve just spotted the perfect sofa online, or you’re finally getting that car you’ve been eyeing. You’re about to whip out your credit card or sign a finance agreeme...
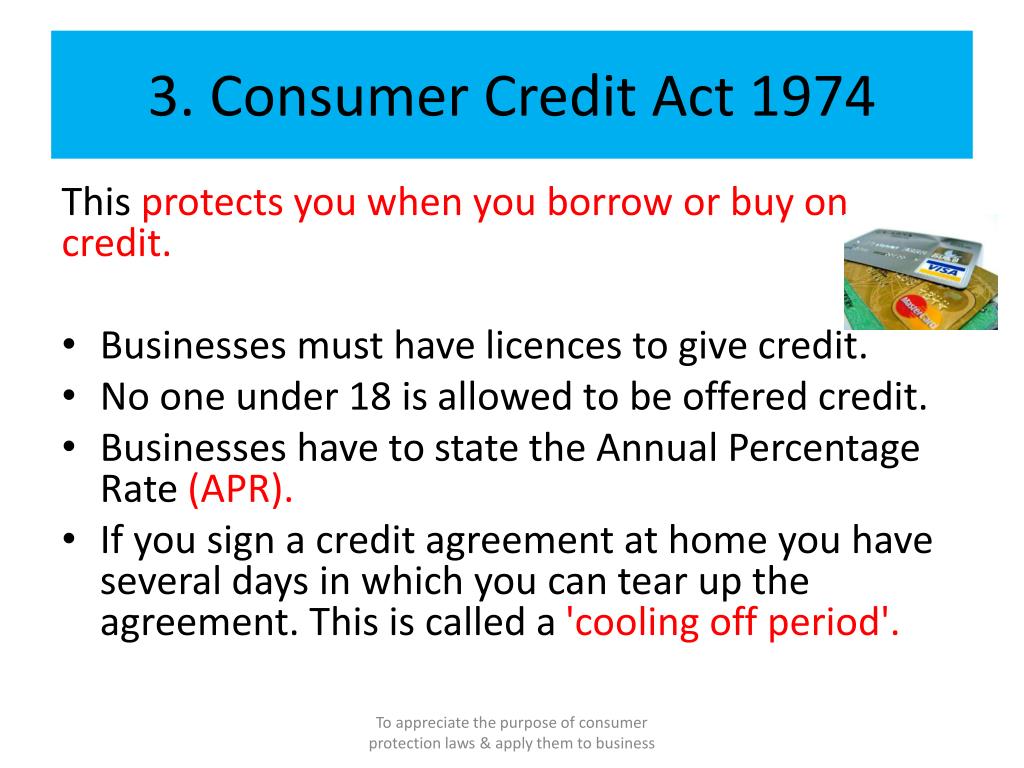
Imagine you’ve just spotted the perfect sofa online, or you’re finally getting that car you’ve been eyeing. You’re about to whip out your credit card or sign a finance agreement when a little voice in your head asks, “What am I actually signing?” That’s where the Consumer Credit Act swoops in like a friendly superhero! It’s your legal shield, making the world of borrowing money or buying on credit feel less like a maze and more like a well-lit path. Trust me, knowing a bit about it can save you from nasty surprises.
The Act’s main purpose is simple: protect you from unfair lending and give you clear rights. When you borrow over a certain amount (like £25 in the UK), lenders must be transparent about interest rates, fees, and your total repayment. Without this law, you might agree to a deal that hides sky-high charges. With it, you get a “cooling-off” period—usually 14 days—to change your mind if you’ve signed a credit agreement at home or online. It’s like having a free trial for your loan!
Here’s where it gets creative: the Act also covers joint liability. Picture this: you buy a faulty laptop on a credit card for £1,000. The shop shuts down, but don’t panic! Under the Act, your credit card provider is equally responsible for the problem. You can claim your money back from them instead. Another fun perk? If you pay for a holiday costing over £100 on your card, the Act protects you if the travel company goes bust. That’s like having a financial safety net woven into your spending!
Must Read
Example time: Say you sign a TV finance deal with a store, and the TV breaks after a week. The store refuses to help. Under the Act, you can demand the lender (the finance company) step in, because they’re jointly liable for the quality of goods bought with the credit. This ties the lender’s reputation to the seller’s performance—making everyone play fair!
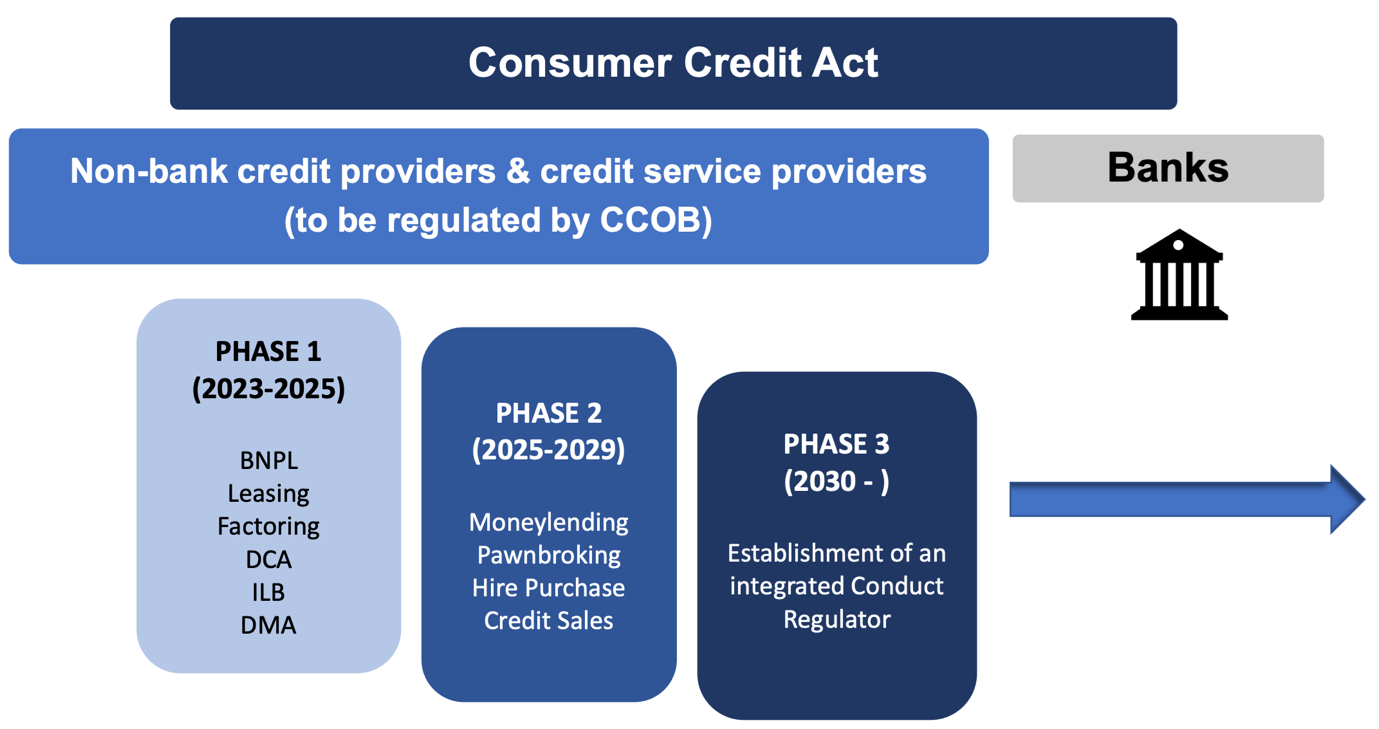 A Peek into Malaysia’s Proposed Consumer Credit Act | One Asia Lawyers
For practical tips, always check your credit agreement’s fine print—look for the words “Total Amount Payable” and “Annual Percentage Rate (APR)”. If the APR isn’t clearly stated, walk away. Also, remember your right to withdraw within 14 days of signing a credit agreement at a distance (like online). Want to test it? Next time you get a “Buy Now, Pay Later” offer, see if the lender provides a pre-contract information sheet—the Act requires it. If they don’t, you might be dealing with a dodgy operator.
Finally, keep a record of all correspondence and payments when using credit. If a dispute arises, the Act gives you a powerful tool to complain to the lender first, then escalate to a free ombudsman service. Don’t be shy—use it! Knowing your rights under the Consumer Credit Act turns you from a passive borrower into an empowered one. So go ahead, buy that sofa or book that trip—you’ve got a legal superpower in your pocket!

