Do I Need Homeowners Insurance For A Rental Property

Welcome to the surprisingly fun world of rental property insurance—yes, you read that right! Thinking about whether you need homeowners insurance for a rental might sound dull...
Welcome to the surprisingly fun world of rental property insurance—yes, you read that right! Thinking about whether you need homeowners insurance for a rental might sound dull, but it’s actually a smart money move that protects your investment and your peace of mind. This article will walk you through the benefits, share some creative scenarios, and give you straightforward advice so you can sleep easy, knowing your property is covered.
First, let’s clear up a major myth: a standard homeowners policy is not designed for a rental. That policy assumes you live there, with your belongings and liability in mind. If you rent it out, the insurer may deny claims—or worse, cancel you. Instead, you need a landlord insurance policy (often called dwelling fire or rental property insurance). Its purpose is to cover the building structure, your liability as a landlord, and sometimes lost rental income if a covered disaster (like a fire) makes the property uninhabitable.
Imagine this: a tenant’s overeager bath bomb clogs the pipes, causing a flood that ruins the kitchen floors. With proper landlord insurance, you’re covered for repairs. Without it, you’re paying out of pocket—and you lose rent while fixing it. Or picture a guest tripping on a loose step. Your liability coverage would help with their medical bills. Insurance turns a potential financial disaster into a manageable hiccup.
Must Read
Another creative advantage: some landlord policies offer rental loss coverage. This pays you a percentage of your monthly rent if the property becomes unlivable due to a covered event. It’s like having a backup paycheck for your property, keeping your cash flow steady while you make repairs. That is pure gold for any landlord.
So, do you need it? Yes, absolutely. A mortgage lender will likely require it if you have a loan, but even if you own the property free and clear, skipping insurance is reckless. Think of it as a safety net—not a luxury. Start by getting quotes for a DP-1 (basic), DP-2 (broad), or DP-3 (special form) policy, depending on your risk tolerance. Compare coverage limits and deductibles like you would for a car.
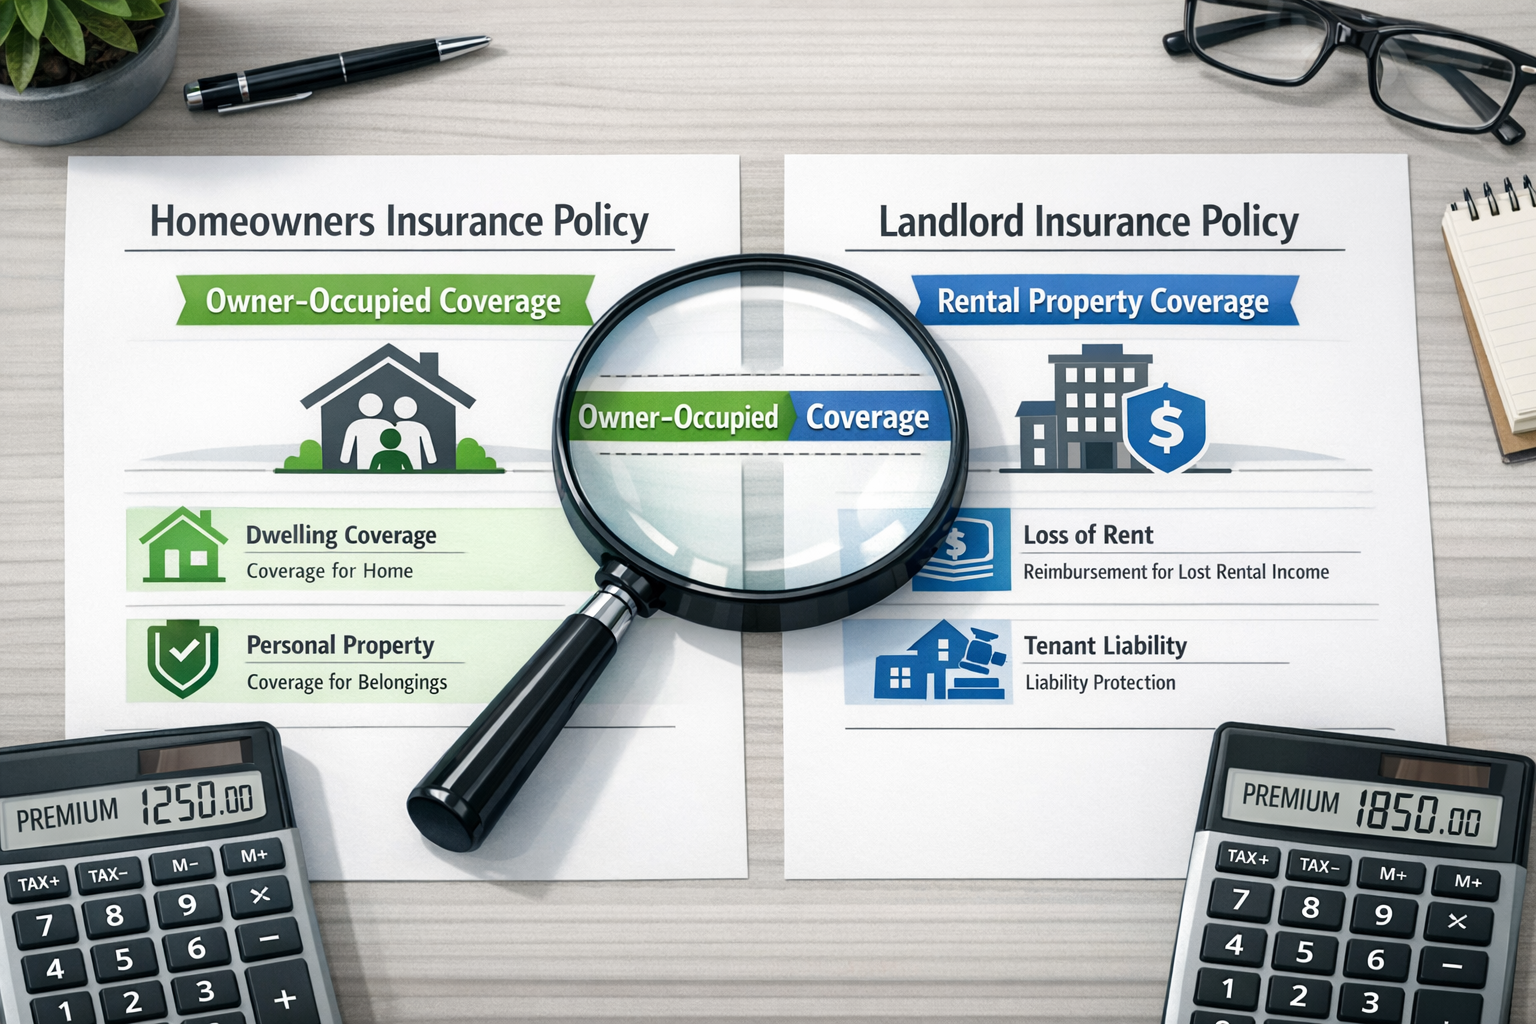 Homeowners vs Rental Property Insurance: 2026 Cost Guide
Quick practical tips: always ask your insurer to add an additional insured endorsement for your property management company (if you use one). Also, require your tenants to have their own renters insurance—that covers their stuff, not yours. Finally, review your policy every year to adjust for rising construction costs or new risks like short-term rentals. A little homework now saves a mountain of headache later.
In short, treating your rental property with the same insurance care as your own home is non-negotiable. It’s not about being paranoid—it’s about being a proactive investor. You’ve worked hard for that property; protect it like the asset it is. Now go forth, insure wisely, and enjoy the rental income with confidence!