Do I Need Landlord Insurance

So, you’re a landlord. Congratulations, you’ve signed up to be the universe’s unpaid plumber, therapist, and midnight raccoon wrangler. You have a tenant, a mortgage, and a pr...
So, you’re a landlord. Congratulations, you’ve signed up to be the universe’s unpaid plumber, therapist, and midnight raccoon wrangler. You have a tenant, a mortgage, and a prayer—but do you actually need landlord insurance? Or is it just another money-sucking creature from the insurance swamp?
Let’s start with a shocker: your regular homeowner’s insurance will laugh in your face if your tenant’s basement pool party floods the place. Seriously, that policy is written for you living there, not some stranger who thinks a “slow drain” is a fun mystery. So unless you enjoy paying for a new floor out of pocket—while your tenant films a TikTok about it—you need separate coverage.
Here’s where it gets juicy. Landlord insurance isn’t just about fixing a broken toilet. It covers liability—like when your tenant’s cousin slips on your “carefully maintained” porch and sues you for a million dollars over a stubbed toe. That’s not a joke; people have literally won cases because of a loose banana peel. I’m not making that up, but I am exaggerating the peel part. Slightly.
Must Read
What Does It Actually Cover?
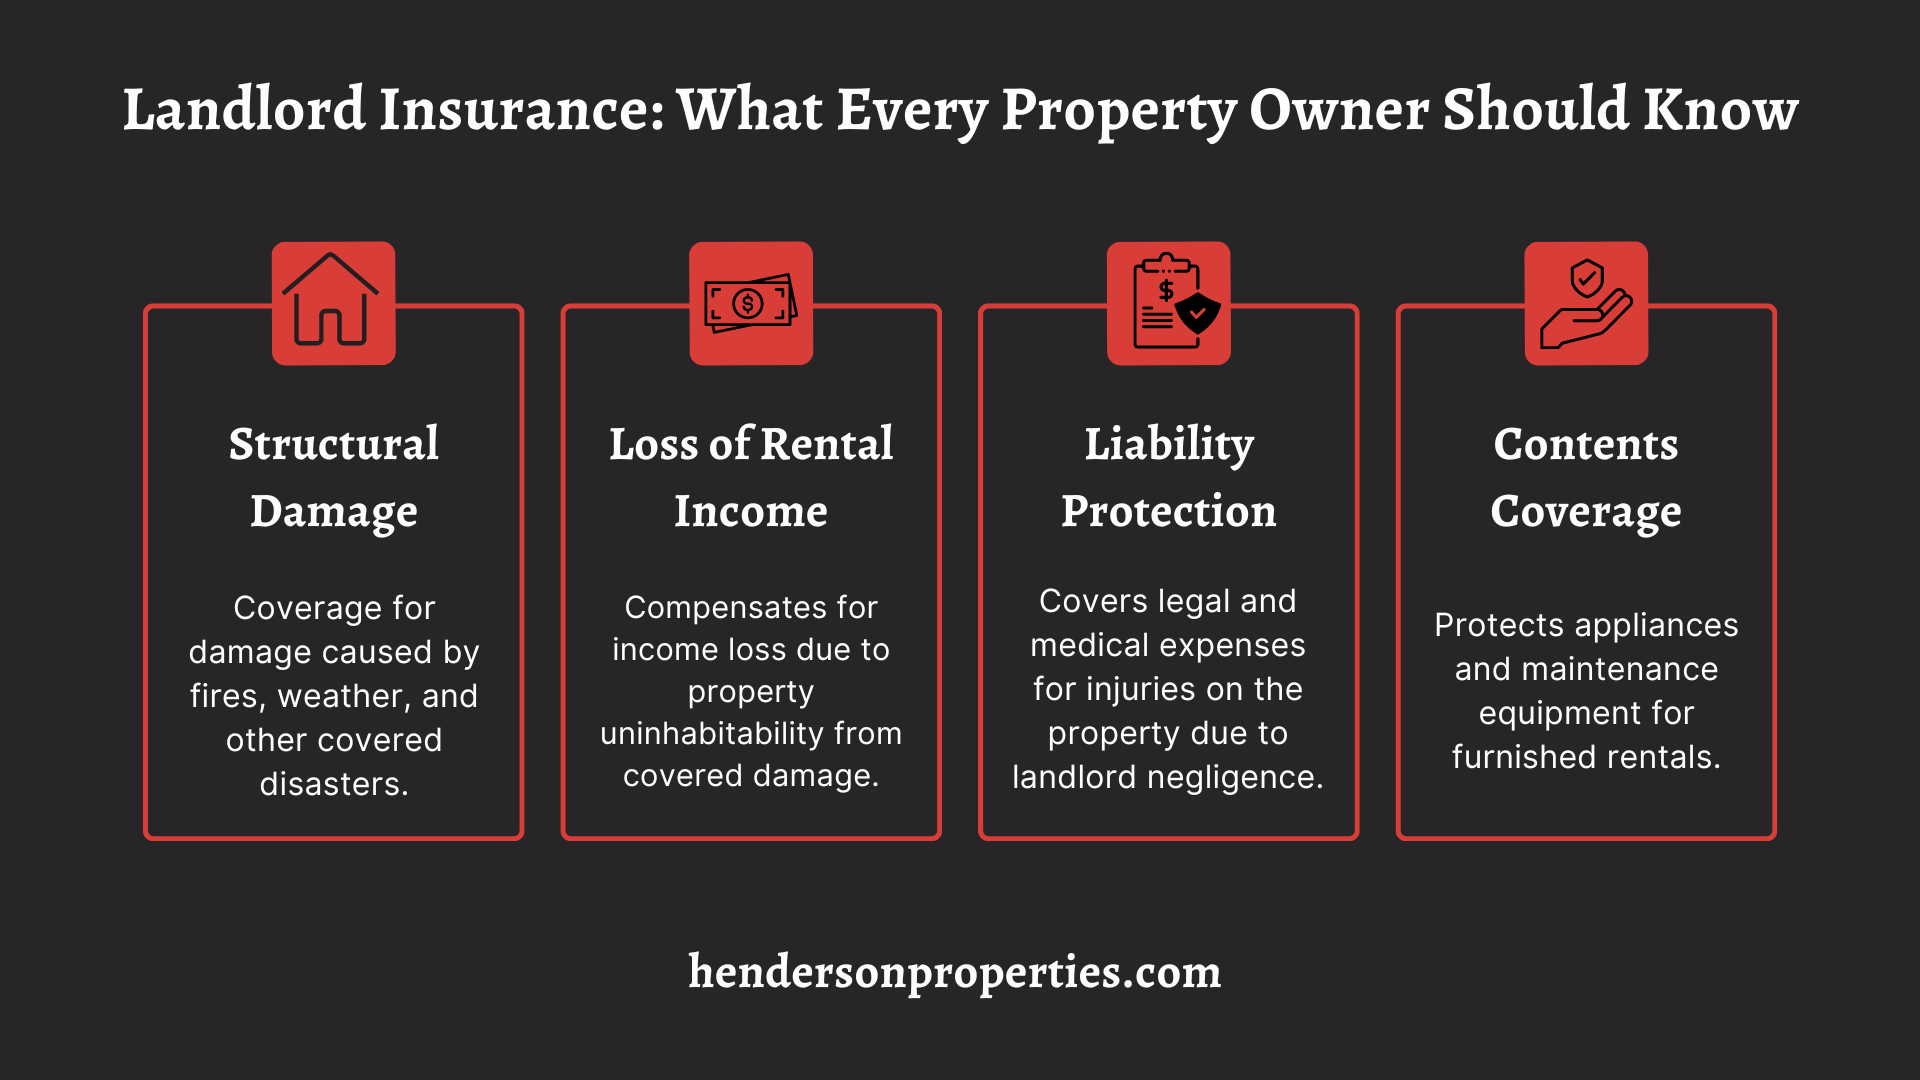
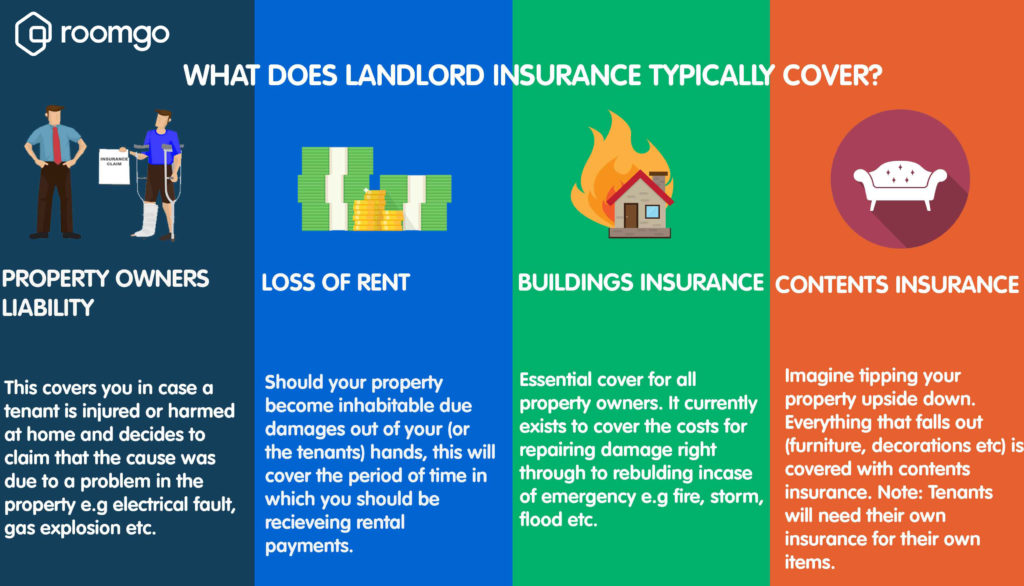
Think of landlord insurance as a superhero with three capes: property damage, liability, and loss of rental income. That third one is your get-out-of-jail-free card if a fire turns your rental into a charcoal sculpture. The insurance will actually pay you the lost rent while it’s being rebuilt. Talk about a plot twist—you get paid for not having a tenant.
But wait, there’s a catch that’ll make you spit out your latte. Standard landlord insurance often excludes natural disasters like floods and earthquakes. Yep, if a river decides to redecorate your basement, you’re on your own unless you buy a separate flood policy. And don’t even get me started on the “mold exclusion” clause—that little fungus can turn your profitable investment into a horror movie set in about three wet weeks.
 How Does Landlord Insurance Work? – WVTC
The “But I’m a Nice Landlord” Trap
I know, I know—you’re the landlord who bakes cookies and never raises rent. Guess what? Raccoons don’t care about your niceness. A raccoon broke into a guy’s attic and caused $20,000 in damage because it decided to chew through wiring and host a rave. Landlord insurance paid for that. Without it? That’s a second mortgage on your emotional stability.
Also, here’s a weird fact: some policies cover legal fees if you have to evict a tenant. Eviction is like a slow-motion car crash with paperwork—costing thousands even before you win. Having insurance that absorbs that lawyer grind is like finding a five-dollar bill in your winter coat, except the bill is five hundred dollars and your coat is on fire.
 How Much Landlord Insurance Do I Need? - Henson Agency
The Verdict: Do You Need It?
If you own a rental property and have a pulse—or even if you’re a ghost who inherited a duplex—yes, you need landlord insurance. It’s not optional unless you enjoy playing financial roulette with a wheel of “freak hail storms” and “tenant’s cat accidentally starting a fire.” One claim can wipe out years of profit, and that’s a funny story for nobody but your accountant.
Bottom line: skip the landlord insurance, and you’re basically saying, “I’d like to donate my savings to a random contractor named Dave.” Get the policy. Sleep better. And if a raccoon throws a party, you’ll at least have wine money left over.
