Do You Need Full Coverage To Finance A Car

There’s something oddly satisfying about the moment you finally decide to finance a car. It’s that mix of practical planning and a little bit of dream-chasing—like picking the...
There’s something oddly satisfying about the moment you finally decide to finance a car. It’s that mix of practical planning and a little bit of dream-chasing—like picking the perfect road trip playlist before you even have the keys. One question almost always pops up: Do you need full coverage? This topic is surprisingly enjoyable because it touches on real-world money decisions without being stuffy. It helps you keep your car safe while balancing your budget, whether you’re a first-time buyer or a seasoned driver eyeing a shiny new ride.
At its heart, the main purpose here is simple: protect your investment and play by the lender’s rules. When you finance a car, the bank or credit union owns a piece of it until you pay off the loan. They want to ensure their asset isn’t wrecked without insurance backing it up. That’s where full coverage comes in—it typically includes collision (for crashes) and comprehensive (for theft, hail, or deer). It’s not just legal; it’s smart peace of mind.
Different people bump into this question in different ways. For a young driver with a used sedan, the lender might require full coverage for the loan term. For someone leasing a luxury SUV, it’s often non-negotiable. A common twist: once you’ve paid off half the loan, you might wonder if you can drop down to liability-only. The answer? Check your contract—most lenders insist on full coverage until the loan is done. Recognizing this helps you avoid surprise fees or a forced policy from the bank.
Must Read
Here’s a simple, actionable tip to get started: call your insurance agent before signing the paperwork. Ask them to run a quote for full coverage on the exact car model you want. This way, you know the monthly hit before the dealership tries to upsell you a policy. Also, compare deductibles—a higher deductible (say, $1,000) lowers your premium, but make sure you can cover that amount if a fender bender happens.
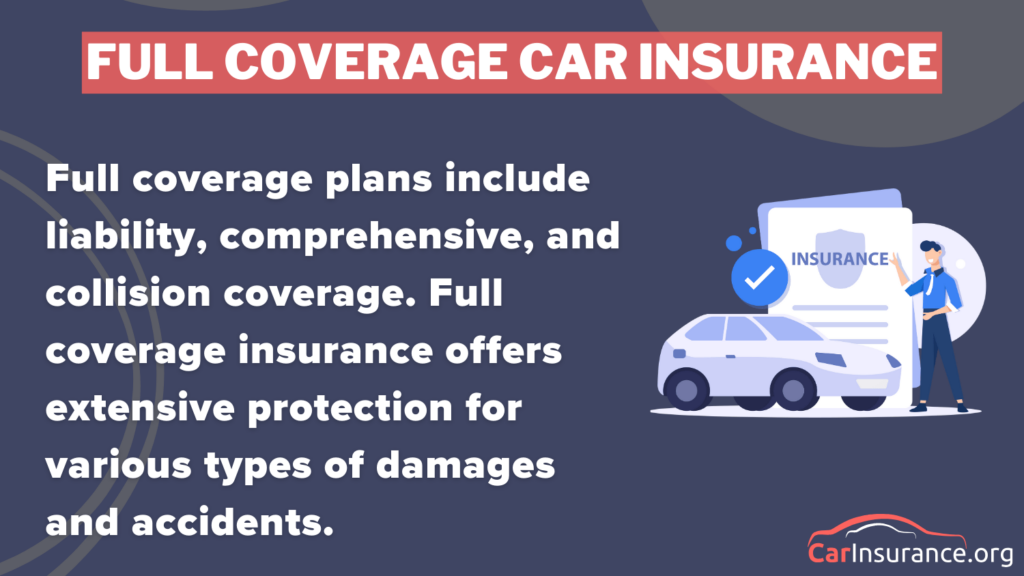 Collision vs. Comprehensive Car Insurance in 2026 (Coverage Comparison
Another handy move: refinance after a year of on-time payments. If your credit score jumps, you might secure a lower interest rate and—bonus—some lenders will let you adjust your coverage requirements. But don’t jump the gun; wait until you’re in the clear and ask explicitly. And always, always read the fine print on your loan agreement. It spells out exactly when you can or can’t drop full coverage.
Remember, full coverage isn’t just a lender’s demand—it’s a tool that saves you from financial whiplash. One bad accident without it could leave you paying off a crumpled loan on a car that’s gone. So, enjoy the process: finance that car, drive it off the lot, and rest easy knowing you’ve covered your bases. It’s practical, and honestly, kind of freeing.

