Does Home Equity Loan Require Appraisal

So, you’re thinking about a home equity loan. Maybe you want to build a pool shaped like a guitar, or finally replace that couch your cat has personally destroyed. But before...
So, you’re thinking about a home equity loan. Maybe you want to build a pool shaped like a guitar, or finally replace that couch your cat has personally destroyed. But before you start shopping for pool floats, a big, scary question looms: do I need an appraisal?
The Short, Slightly Painful Answer
Yes, almost always. Lenders are basically paranoid babysitters with calculators. They need to know your house isn’t a cardboard box painted to look like a mansion.
Think of it this way: they’re lending you money based on your home’s value. Would you lend your friend $5,000 because he claims his comic book collection is worth a fortune? No. You’d demand proof, and probably a sandwich for collateral.
Must Read
Why Can’t They Just Trust Me? My House is Charming!
Ah, the classic homeowner delusion. Your “charming” closet is actually a crawlspace that smells like damp ferret. An appraiser is the cold, hard truth in khaki pants. They measure everything, poke at the foundation, and judge your paint color choices silently.
Here’s a surprising fact: appraisers don’t care about your new marble countertops if the roof leaks like a sieve. They’re paid to be brutally honest. One guy in Ohio once had his loan denied because his bathroom was entirely wallpapered with beer labels. Apparently, that counts as “unsafe.”
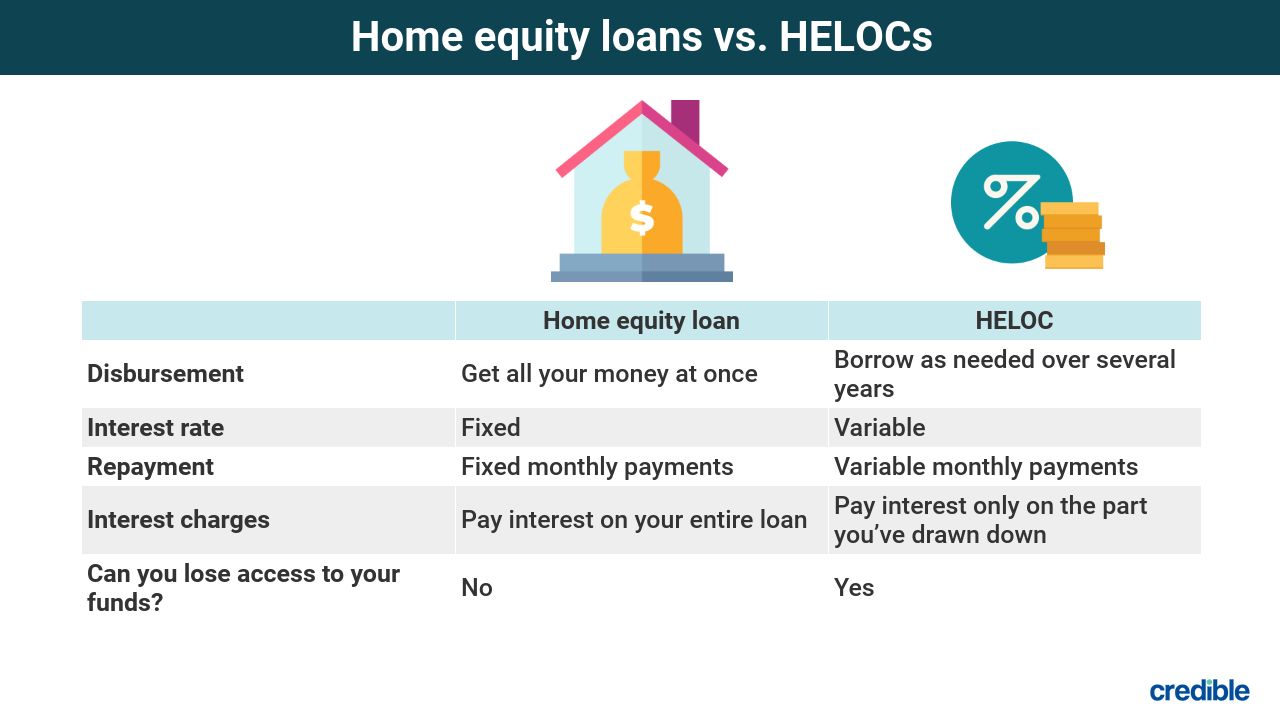 Home Equity No Appraisal at Chris Henry blog
But Wait! Is There a Magical Loophole?
Sort of! Some lenders offer a “drive-by appraisal” or a “desktop appraisal.” This is where they look at your house from the street—or just Google Earth. It’s like judging a book by its cover, but for mortgages. It’s faster, cheaper, and slightly less invasive than having a stranger measure your closet.
However, this only works if your home is in a cookie-cutter neighborhood where every house looks identical. If you live in a geodesic dome shaped like a turtle, expect the full inspection. They will check your turtle’s shell for cracks.
What If the Appraisal Comes Back Low?
Oof. This is the financial equivalent of stepping on a Lego. Your loan amount shrinks, your pool plans turn into a kiddie wading pool. But here’s the joke: you can dispute it! You can argue, cry, or show the appraiser photos of your “renovated” bathroom (the one where you fixed the leaky faucet last Tuesday).
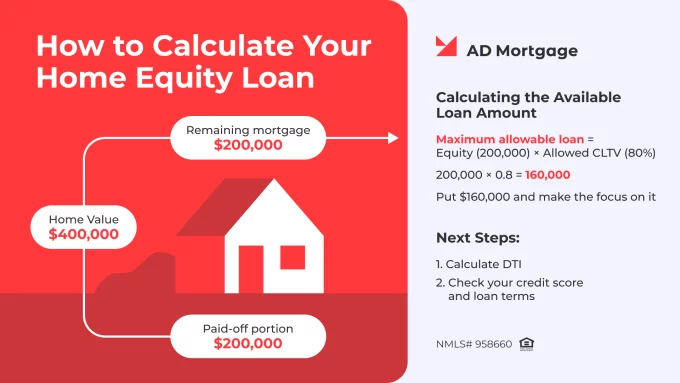 Home Equity Loan: Insights for Mortgage Brokers | AD Mortgage
Surprising fact: Appraisals can vary by $20,000 or more just based on the appraiser’s mood or the time of day. One study found that appraisals done on rainy days are lower. So maybe schedule yours during a sunny, post-lunch, caffeine-rush hour. True story.
The Bottom Line (Stop Squinting)
You probably need an appraisal. It’s like a colonoscopy for your house: uncomfortable, expensive, but ultimately reassuring. Without it, the bank is just guessing, and they hate guessing—unless it’s about who will default on a loan next. They’re excellent guessers for that.
So, get the appraisal. Clean your house first. Hide the ferret smell. And remember: the appraiser is not your friend, but they’re also not your enemy. They’re just a professional photocopier of reality. Just don’t offer them coffee. It slows them down.
