Finance Rates For Rv

So, you’re thinking about an RV? That’s awesome. You’re not just buying a vehicle; you’re buying a ticket to weekend campfires and spontaneous road trips. But let’s be real fo...

So, you’re thinking about an RV? That’s awesome. You’re not just buying a vehicle; you’re buying a ticket to weekend campfires and spontaneous road trips. But let’s be real for a second—how do you actually pay for that dream machine without sweating through your bank account?
That’s where finance rates for RVs come into the picture. They’re basically the price of borrowing money, but they can feel a bit mysterious, right?
Think of an RV loan like a mortgage for a tiny house on wheels. The interest rate is the toll you pay for using the bank’s cash to get on the highway faster.
Must Read
Why Your Credit Score is Like a VIP Pass
Here’s the deal: your credit score is the main character in this story. A high score whispers to lenders, “Hey, this person pays their bills.” A lower score? It might scream, “Woah, hold on, let’s charge a little extra just in case.”
Ever tried getting into a concert? A great credit score is like a backstage pass. It unlocks the lowest rates and the best terms. A rough score might mean you’re stuck in the nosebleed seats with a higher APR.
But don’t panic if your score isn’t perfect. Lenders look at your debt-to-income ratio too. It’s like checking if your plate is too full before adding another helping of RV payments.
New vs. Used: The Cool Factor vs. The Bargain Bin
New RVs smell like adventure and have that shiny, untested vibe. The catch? Finance rates for new rigs are often lower because the bank knows it’s a fresh asset that holds value (for a little while, anyway).
 Campervan Questions Part 2: What Does Buying a Campervan Look Like?
Used RVs, on the other hand, are like finding a vintage leather jacket. They’re cheaper upfront, but the interest rate might be a bit higher. It’s the bank’s way of saying, “This thing has miles and a story—we need some extra security.”
Which one sounds more like you? A brand-new adventure mobile, or a well-loved wanderer with character? Both are cool, but the rate will nudge you toward one path.
Loan Terms: The Tortoise or the Hare?
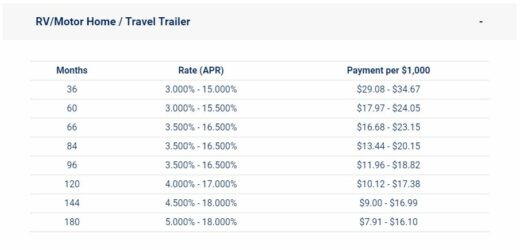
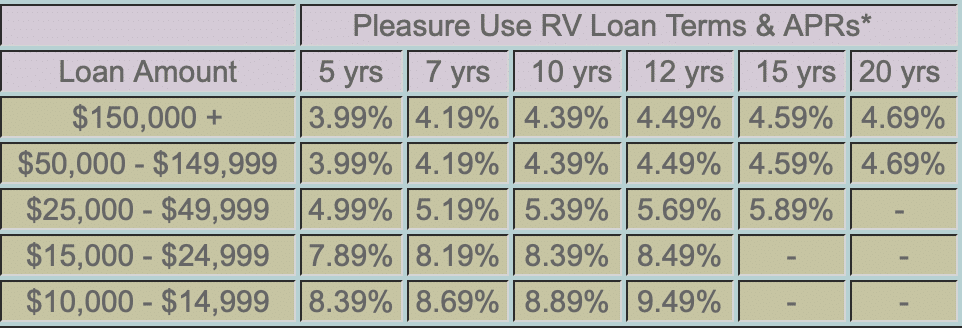
You get to choose how long you want to pay. A shorter term (say, 3 to 5 years) usually gives you a lower interest rate. The trade-off? Higher monthly payments. It’s like sprinting—you finish fast but work harder each month.
Then there’s the long game: 10, 15, even 20 years. These stretch out the payments, making them feel lighter on your wallet each month. The catch is a higher rate overall because the bank is waiting longer to get their money back.
 Best RV Loan Rates to Finance Your Next Camper - The Wandering RV
So, are you the tortoise, slow and steady, or the hare, quick and done? There’s no wrong answer—it’s about what fits your life right now.
Where to Look for the Best Deals
Don’t just walk into a dealership and sign the first paper they slide at you. That’s like buying a taco from the first stand you see without checking the menu next door. Shop around!
Credit unions often have killer rates for RVs, and they’re usually friendlier than big banks. Online lenders can also be great for comparison shopping. You have the power to say, “This rate? Nah, I’ll pass.”
One last tip: put down a solid down payment. Like, 20% or more. It lowers the lender’s risk, which can lower your rate. It’s like showing you’re serious about the whole “adventure life” thing.
So, ready to roll? Just remember: finance rates are the road map, not the destination. Keep your credit shiny, compare your options, and soon you’ll be closer to that sunset view from your own front yard—on wheels.
