Homeowners Insurance For A Rental Property

So, you’ve got a rental property. Maybe it’s a cozy apartment or a beachside shack. You’re collecting rent, and things are going smoothly. But have you ever wondered if your s...
So, you’ve got a rental property. Maybe it’s a cozy apartment or a beachside shack. You’re collecting rent, and things are going smoothly. But have you ever wondered if your stuff is actually protected if a pipe bursts?
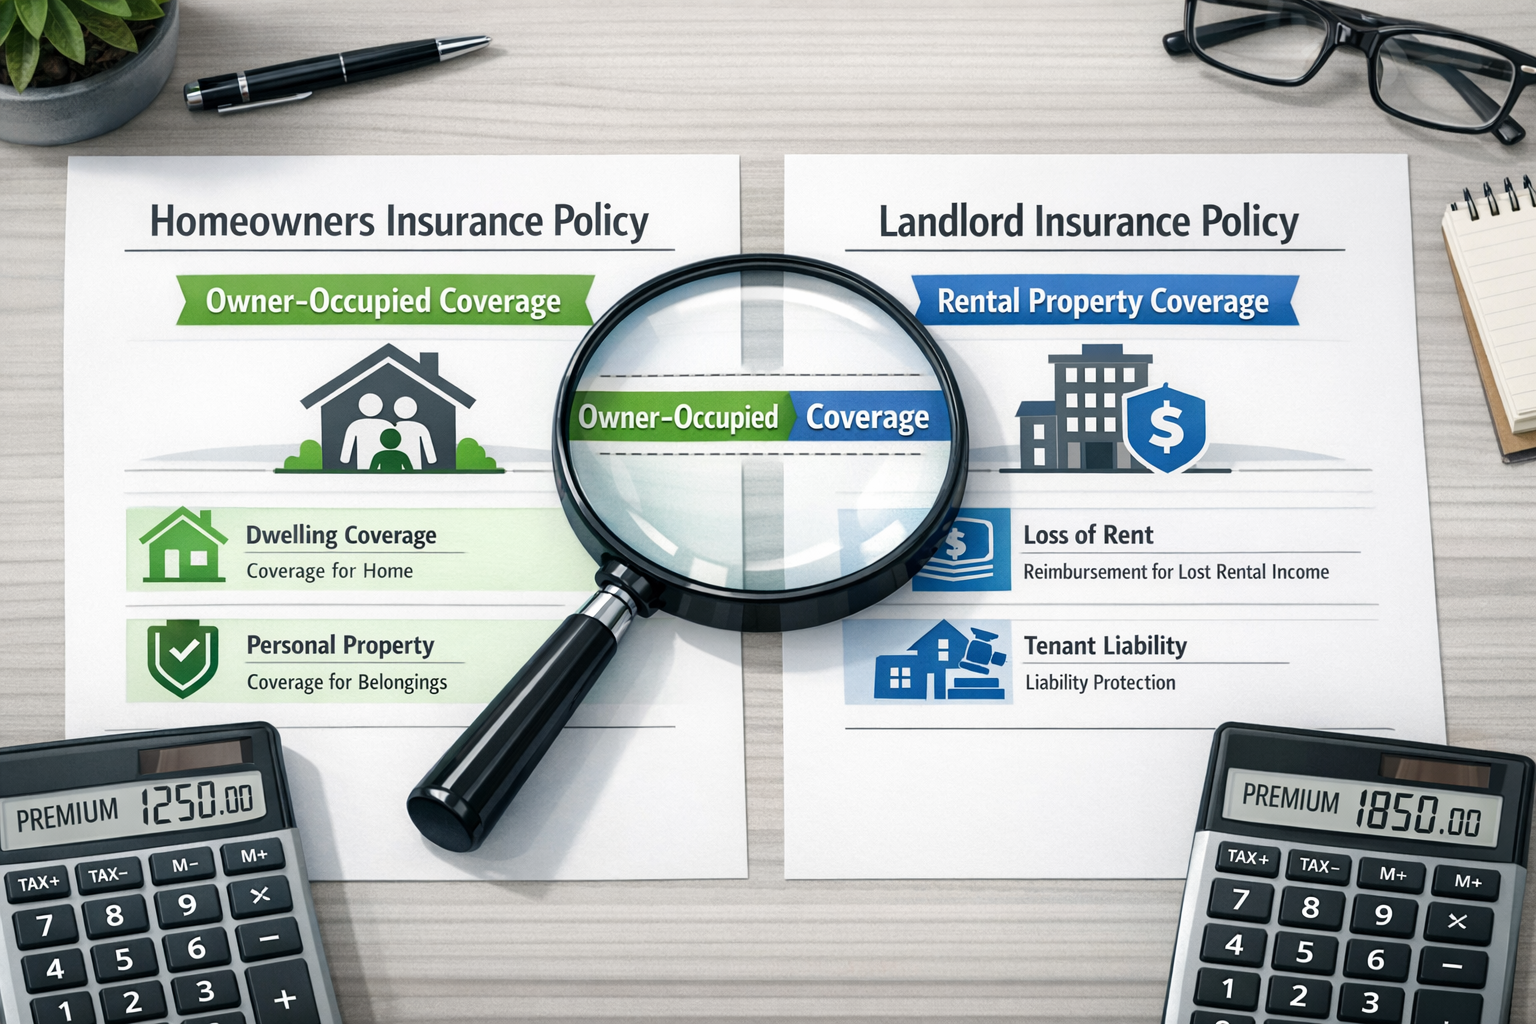
Here’s the deal: homeowners insurance for a rental isn’t the same as your regular home policy. Think of it like the difference between wearing a swimsuit to the pool and wearing one to a hurricane. Totally different vibes!
Your standard homeowners insurance is designed for you living there. It’s like a warm blanket for your favorite couch. But when you rent it out, the insurer sees a whole new level of risk—like strangers with a bonfire in the backyard.
Must Read
So, what do you actually need? You want landlord insurance. It’s a special breed that covers your building, but not your tenant’s belongings. Imagine it as a shield for the house itself, not for the party inside.
Why It’s Actually Cool
This isn’t just boring paperwork. Landlord insurance is like a secret superhero cape. If a tree crashes through the roof or a kitchen fire erupts, you’re covered for repairs and lost rent.
Lost rent? Yep! That’s a sweet perk. If a disaster makes the place unlivable, this policy pays you while the tenant crashes elsewhere. Cha-ching—your bank account stays happy.
Compare that to a regular homeowners policy, which might laugh and say, “Sorry, that’s your tenant’s problem now.” Ouch, right? You’d be stuck paying the mortgage on an empty wreck.
 Liability insurance for vacation rental property Top 1
What Gets Tricky?
Here’s the funny part: your tenant’s stuff isn’t your headache. If their laptop is stolen or their inflatable pool explodes, that’s on them. They need renter’s insurance, not you.
But don’t snooze on liability coverage. If your tenant’s guest trips over a loose step and sues you, landlord insurance has your back. Without it, you could be counting pennies for a lawyer.
And please, read the fine print. Some policies have a “vacancy clause” that stops coverage if the place is empty for 30 days. Imagine your property standing alone, vulnerable, while you’re at brunch. Scary, huh?
The Dollar Question
Is landlord insurance more expensive? It depends. Usually, it’s about 15-25% more than a regular home policy. But think of it as buying peace of mind instead of a cheap umbrella that flips inside out.
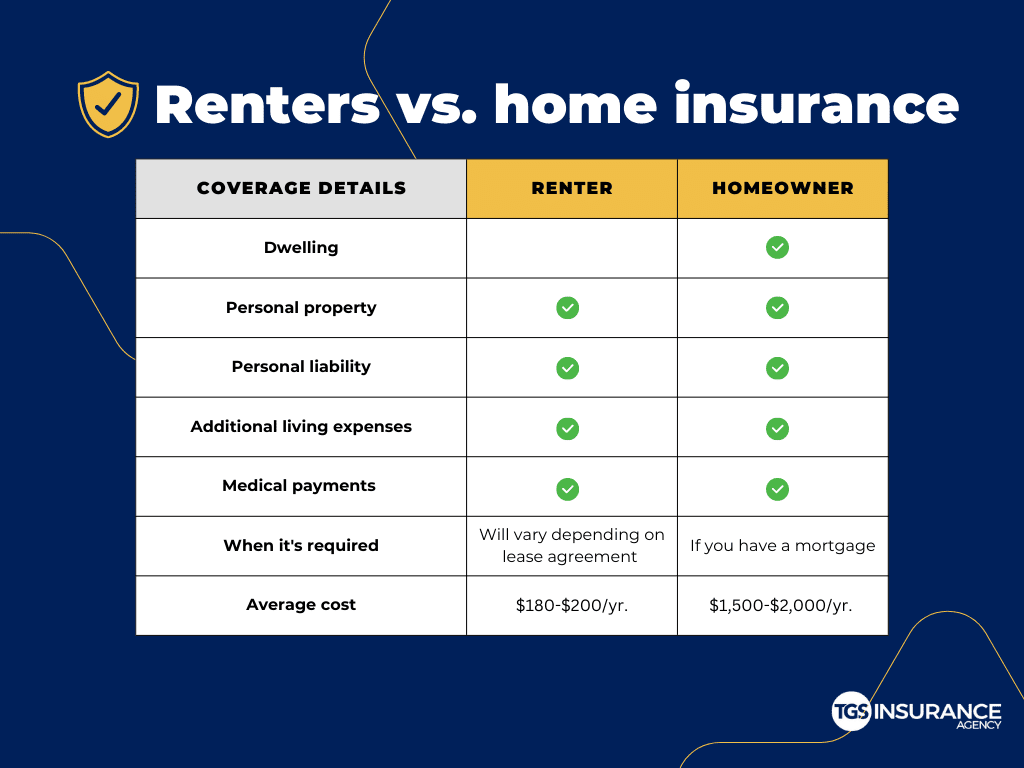 Renters Insurance vs Homeowners Insurance Explained
Shop around. Bundle it with your other insurance for discounts. And ask about “fair rental value” coverage—it’s the MVP if a fire forces your tenant out for three months.
One more tip: update your policy if you raise rent or renovate. You wouldn’t drive a sports car with tricycle insurance, right? Same idea.
So, Should You Get It?
If you own a rental property, yes. Skipping landlord insurance is like jumping out of a plane and hoping for a friendly cloud. Low chance of a happy landing.
Think of it this way: your rental is a little money machine. Protect that machine with the right insurance. It’s not boring—it’s brilliant, like wearing a seatbelt without planning to crash.
Ready to feel like a boss? Call your insurer today. Ask them, “What’s my best landlord policy?” You’ll sleep better, and your property will thank you.
