Homeowners Insurance On A Rental Property

For many, owning a rental property is the ultimate expression of financial independence. It offers a steady stream of passive income and the profound value of building long-te...
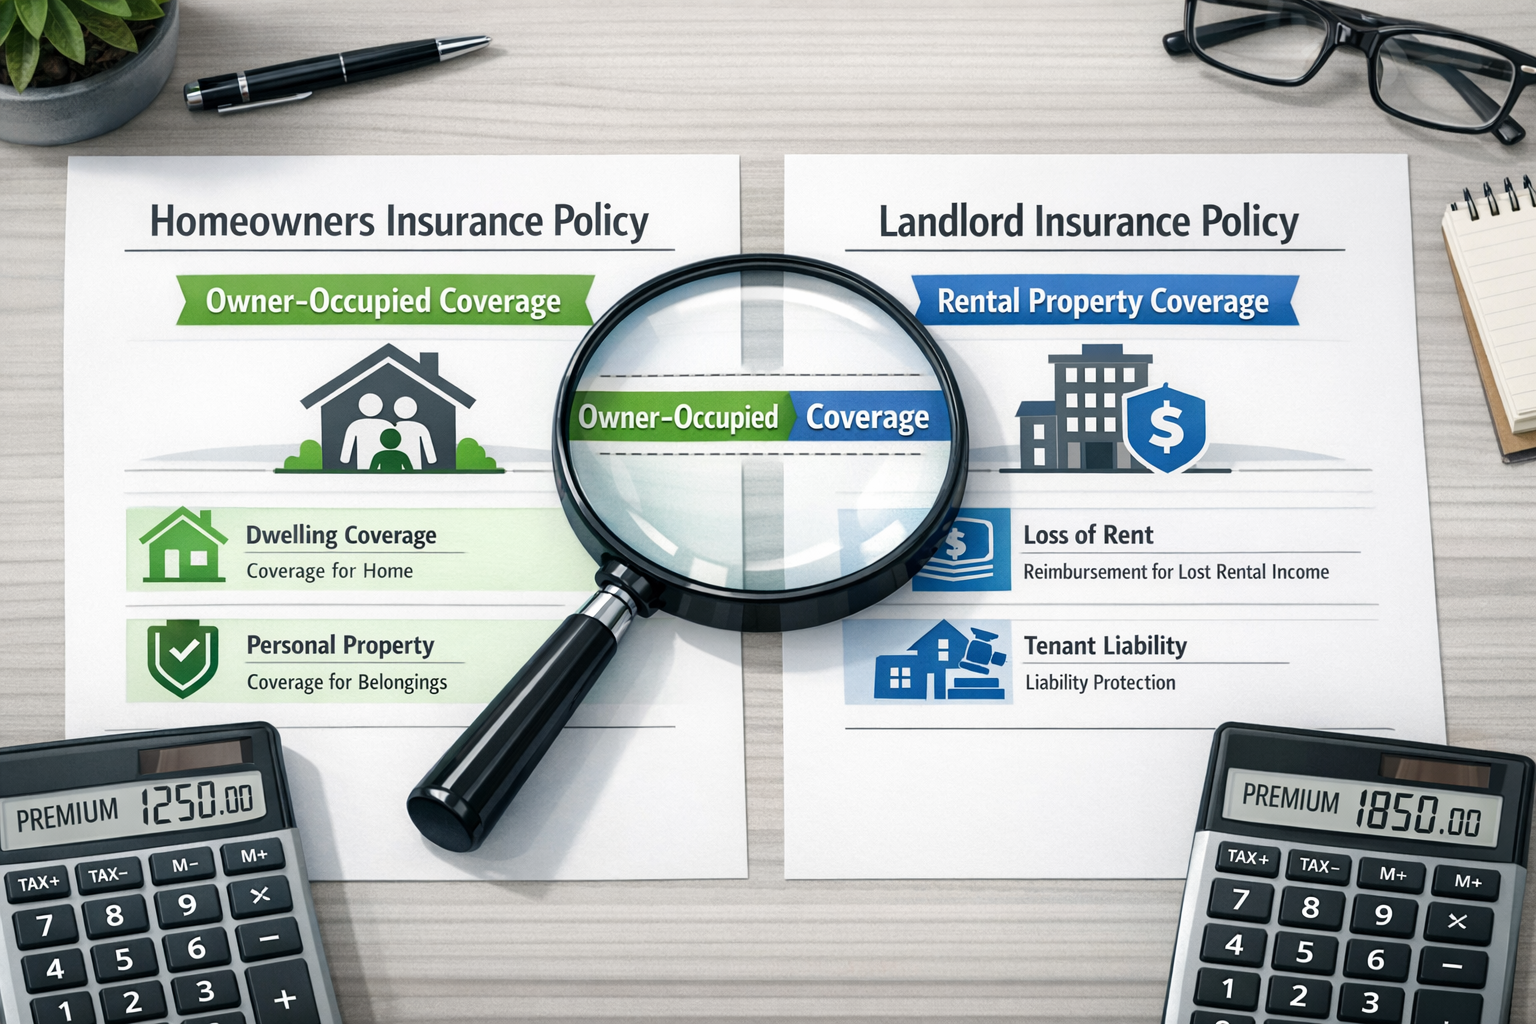
For many, owning a rental property is the ultimate expression of financial independence. It offers a steady stream of passive income and the profound value of building long-term wealth through real estate. The dream of a tenant paying your mortgage is a powerful motivator, but that dream requires a solid foundation of protection.
The key purpose of homeowners insurance on a rental property is fundamentally different from a standard policy. While a personal policy protects your belongings and liability as an occupant, a landlord policy focuses on protecting the structure and your investment from unique risks. It covers the dwelling itself—the roof, walls, and foundation—against fire, wind, and vandalism, but it specifically excludes the tenant’s personal items. This distinction is critical for preventing a devastating financial loss.
The real-world benefits are tangible and invaluable. Imagine a tenant accidentally leaves a stove burner on, causing a kitchen fire. Your landlord policy would help pay for the repairs and the loss of rental income while the property is being fixed. Without it, you would face thousands in out-of-pocket costs. Similarly, if a guest slips on an icy walkway and sues you, the liability coverage in your policy protects your personal savings from being wiped out by legal fees and settlements.
Must Read
This coverage also gives you peace of mind every single month. Instead of worrying about every midnight call from a tenant, you can sleep easier knowing you have a financial safety net. It allows you to treat your rental as a professional business, not a constant source of anxiety. This stability is what empowers you to scale your portfolio and grow your passive income stream over time.
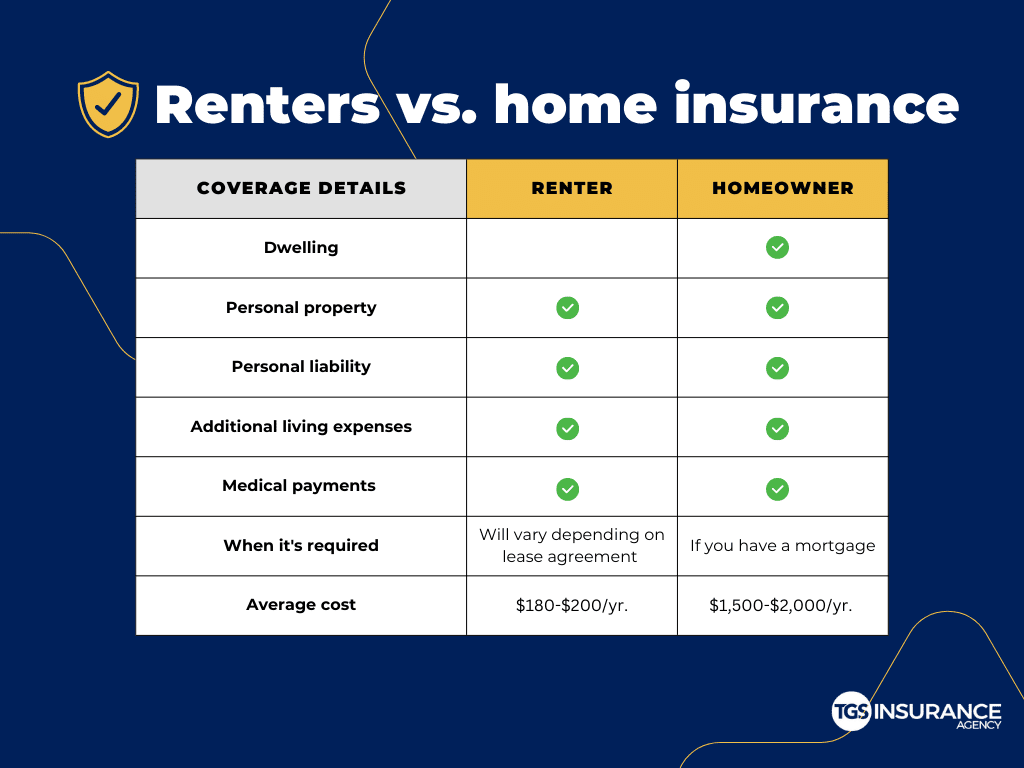 Renters Insurance vs Homeowners Insurance Explained
To get started exploring your own coverage, first never assume a standard homeowners policy will work. Contact an insurance agent who specializes in landlord insurance. Ask them specifically about dwelling fire and fair rental value coverage. These are not optional add-ons; they are the core components of a rental policy.
Another simple tip: always document your property with photos and a video before renting it out. This makes filing a claim for damage much smoother. Finally, understand your deductible. A lower deductible means a higher premium, but in a real emergency, it can save you significant stress. Consult a local agent to tailor your coverage to your specific property and budget.