Macro And Microeconomics

There’s something quietly fascinating about understanding the forces that shape your daily life, from the price of your morning coffee to the job market you navigate. Macro an...
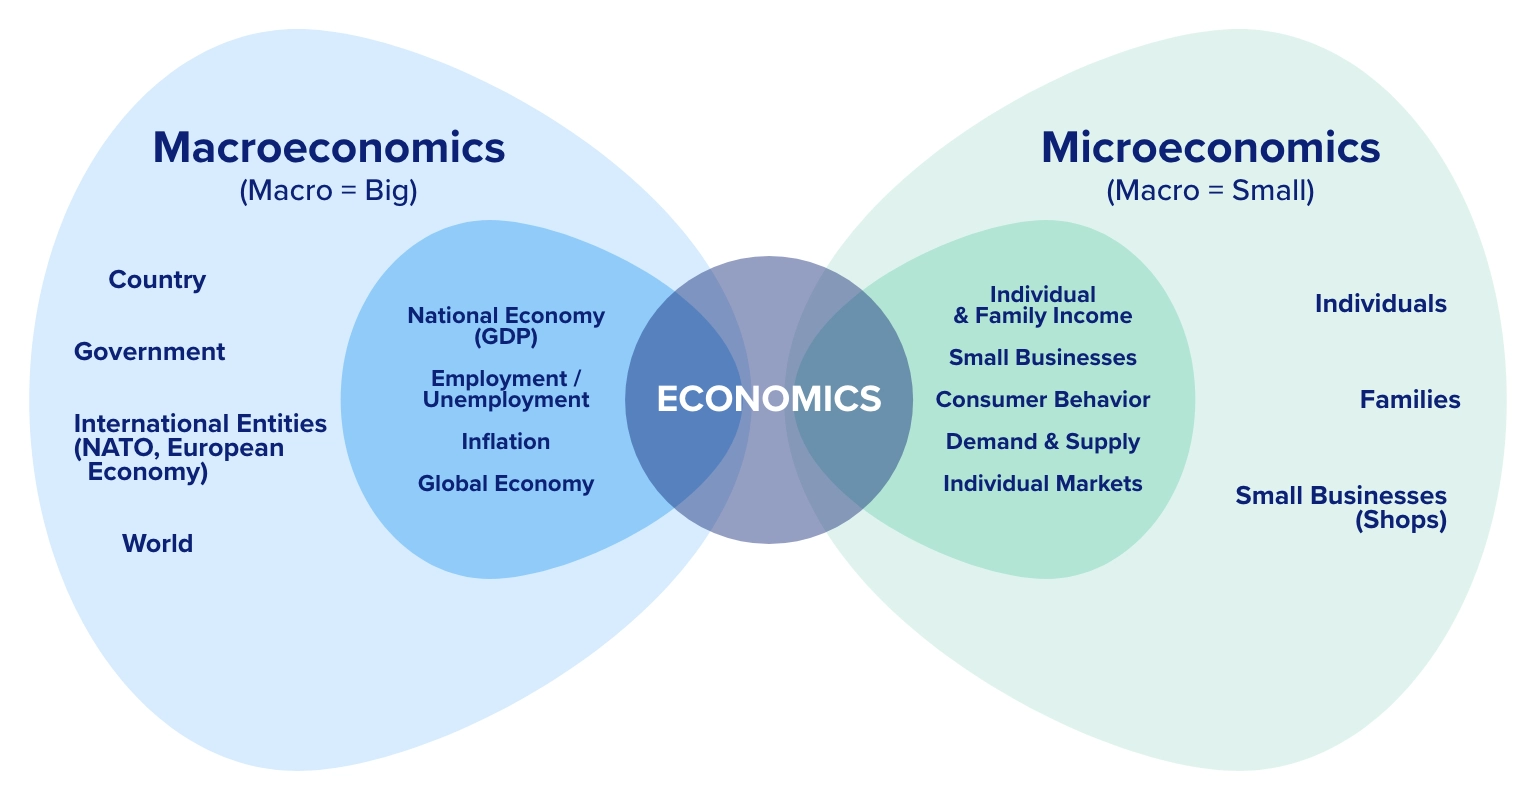
There’s something quietly fascinating about understanding the forces that shape your daily life, from the price of your morning coffee to the job market you navigate. Macro and microeconomics might sound like dry textbook terms, but they’re actually a practical lens for seeing why things happen the way they do—and that makes them surprisingly enjoyable. At their core, these two fields help us answer two simple questions: “Why did that happen to me?” and “What’s happening to everyone?” Whether you’re a business owner setting prices, a student planning a budget, or just someone who wonders about inflation, this knowledge brings clarity and a bit of control to a chaotic world.
Microeconomics zooms in on the small stuff—the choices you and I make as individuals. It explains why a bakery raises its croissant price when flour costs spike, or why you might opt for a bus pass instead of a rideshare when gas prices jump. Its main purpose is to help you see the trade-offs in every decision, from your morning commute to your Netflix subscription. For a small business owner, understanding microeconomics can mean smarter pricing and better inventory management. For you, it’s a tool to stretch your paycheck further.
Then there’s macroeconomics, which takes the wide-angle view—think big-picture trends like unemployment, inflation, and national growth. You’ve bumped into it every time you hear news about interest rate hikes or a recession rumor. Macroeconomics helps governments decide when to stimulate the economy or when to cool it down. For regular people, it explains why your rent might climb even if your salary stays flat, or why student loan interest rates are tied to central bank policies. It’s the weather report for the economy, and knowing it helps you plan for storms.
Must Read
Common variations of these ideas show up all around you. Ever noticed that during a holiday sale, stores slash prices on old inventory while luxury brands rarely budge? That’s microeconomics—supply and demand in action. Meanwhile, if you’ve seen headlines about a government stimulus check or a new trade tariff, you’re witnessing macroeconomics at work. These two fields aren’t separate; they’re two sides of the same coin, each explaining a different layer of your financial reality.
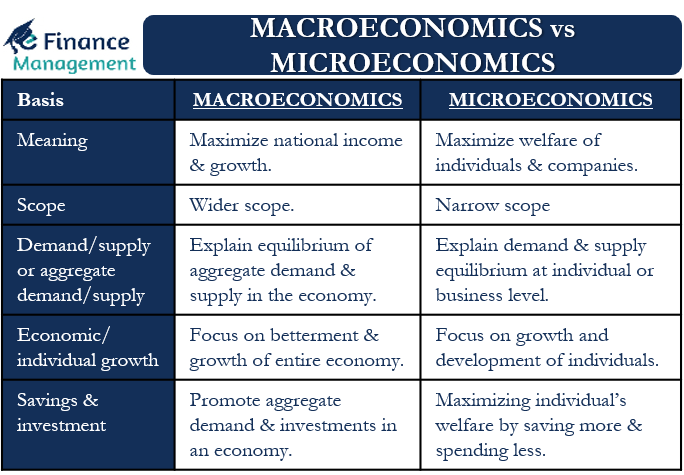 Economics - Page 3 of 4 - eFinanceManagement
Getting started is simpler than you think. First, observe one small price change today—perhaps the cost of gasoline or a grocery staple—and ask yourself: “Is this micro (local supply) or macro (global oil prices)?” Second, skim a headline about economic data, like the unemployment rate, and note how it affects your industry or job security. Third, practice the one-question test: if the issue affects your personal budget, it’s micro; if it shapes the entire country’s spending power, it’s macro. You don’t need a degree—just curiosity and a habit of noticing the patterns around you.
The real benefit comes when you start using this split vision daily. Macroeconomics helps you make bigger moves, like deciding when to buy a house or invest in a retirement fund. Microeconomics sharpens your day-to-day choices, from negotiating a raise to choosing a phone plan. Together, they turn financial confusion into a manageable map. So next time you hear about GDP or see a “buy one, get one” deal, pause and smile—you’re now reading the hidden language of your world.

