North American Firearms Lombard

Imagine, if you will, a world where a bank’s chief loan officer also moonlights as a gun-slinging diplomat. Welcome to the chaotic, hilarious history of the North American Fir...
Imagine, if you will, a world where a bank’s chief loan officer also moonlights as a gun-slinging diplomat. Welcome to the chaotic, hilarious history of the North American Firearms Lombard—a business so bizarre it sounds like a joke from a 19th-century saloon. It wasn't a bank, but it acted like one, except instead of lending you cash, it lent you guns.
The Weirdest Bank You Never Heard Of
Founded in 1871 in New York City, the North American Firearms Lombard was a pawnbroker of epic proportions, specializing almost exclusively in firearms. Its founder, a clever fellow named William B. McCormick, realized that in the chaotic years after the Civil War, guns were everywhere—and so were broke people. He offered loans in exchange for your revolver or rifle, charging interest like any bank.
But here’s the punchline: the Lombard didn't just store these guns; it turned around and sold the ones that weren’t claimed. It became the world’s first gun “superstore” with a banking license. You could walk in, pawn your Colt .45, and if you didn’t come back in 90 days, that same gun would be on the display case for sale.
Must Read
The Gun That Traveled West
Here’s a surprising fact: the Lombard essentially invented the secondary market for firearms. Out-of-work Union soldiers would pawn their weapons for a train ticket west, and the Lombard would sell those very guns to settlers heading to the frontier. Think of it as the Uber of Wild West armories—except with more rust and less app support.
By the 1880s, the company had millions of dollars in inventory, including rare Colts and Winchesters. They even issued their own paper currency—literally, loan tickets—which some people used as money. Imagine paying for a drink with a slip that says, “I owe you one Smith & Wesson.”
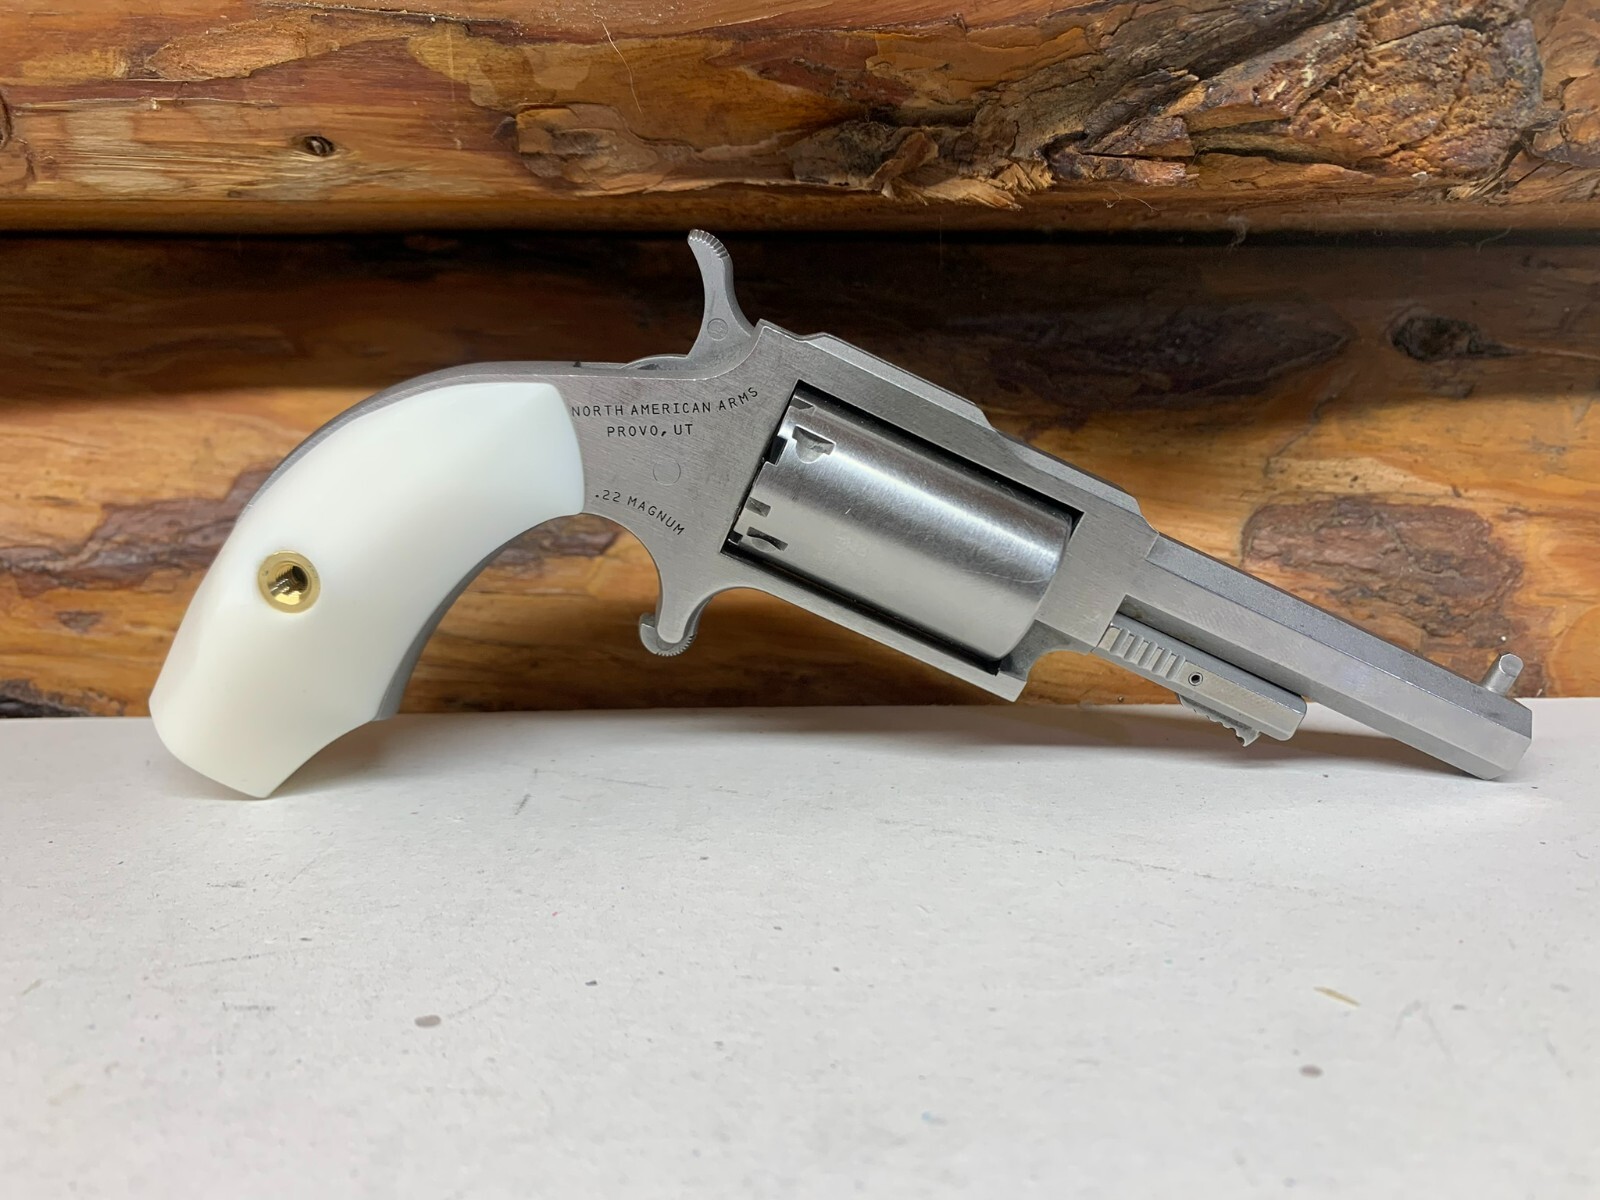 LARGE SMOOTH NAA 22 MAG EXTENDED GRIP, NORTH AMERICAN ARMS GRIPS W
When Greed Met Gunpowder
Eventually, the Lombard’s founders got greedy. They started making loans at outrageous interest rates (up to 36% annually), which was legal but morally sketchy, even by 1880s standards. Customers began defaulting en masse, and the company was flooded with thousands of unclaimed guns—so many that they had to rent an entire warehouse.
Then came the Panic of 1893, a financial depression that would make 2008 look like a picnic. The Lombard, now sitting on a mountain of unsold revolvers and rifles, went bankrupt. It was a poetic ending: a business that thrived on debt was ultimately destroyed by it. Oops.
 LARGE SMOOTH NAA 22 MAG STYLE 2 EXTENDED GRIP, NORTH AMERICAN ARMS
What We Can Learn from This Madness
The North American Firearms Lombard was a perfect storm of capitalism, violence, and terrible financial planning. It shows us that even in the Wild West, someone was trying to figure out how to pawn a shotgun to pay rent. And yes, they absolutely called it the “Lombard” because it was a loan operation—not because it had a mustache and a funny accent.
Today, you can still find old Lombard loan tickets in antique shops, serving as a weird reminder that people will always need money, and guns are surprisingly liquid assets. So next time you’re at a pawn shop, remember: you’re standing in the shadow of a 19th-century financial genius who thought, “Why not treat a revolver like a savings account?” Brilliant. Or insane. Probably both.
