Renting Your Home Insurance

So, you’ve finally snagged that dream apartment—congrats! You’ve got the perfect throw pillows, a monstera plant that *might* survive, and a fancy coffee maker. But wait—did y...
So, you’ve finally snagged that dream apartment—congrats! You’ve got the perfect throw pillows, a monstera plant that might survive, and a fancy coffee maker. But wait—did you remember to actually rent your home insurance? I know, I know, it sounds about as exciting as watching paint dry. But stick with me; this is the good stuff, I promise.
First off, let’s bust a myth: your landlord’s insurance? Covers their building. Not your vintage vinyl collection or that laptop you use for, uh, “work.” That’s on you, buttercup. Renting insurance is like a cozy security blanket for your stuff. If a pipe bursts and turns your living room into a mini pool, or your neighbor’s questionable cooking habits start a small fire, your policy steps in to say, “I got your back.”
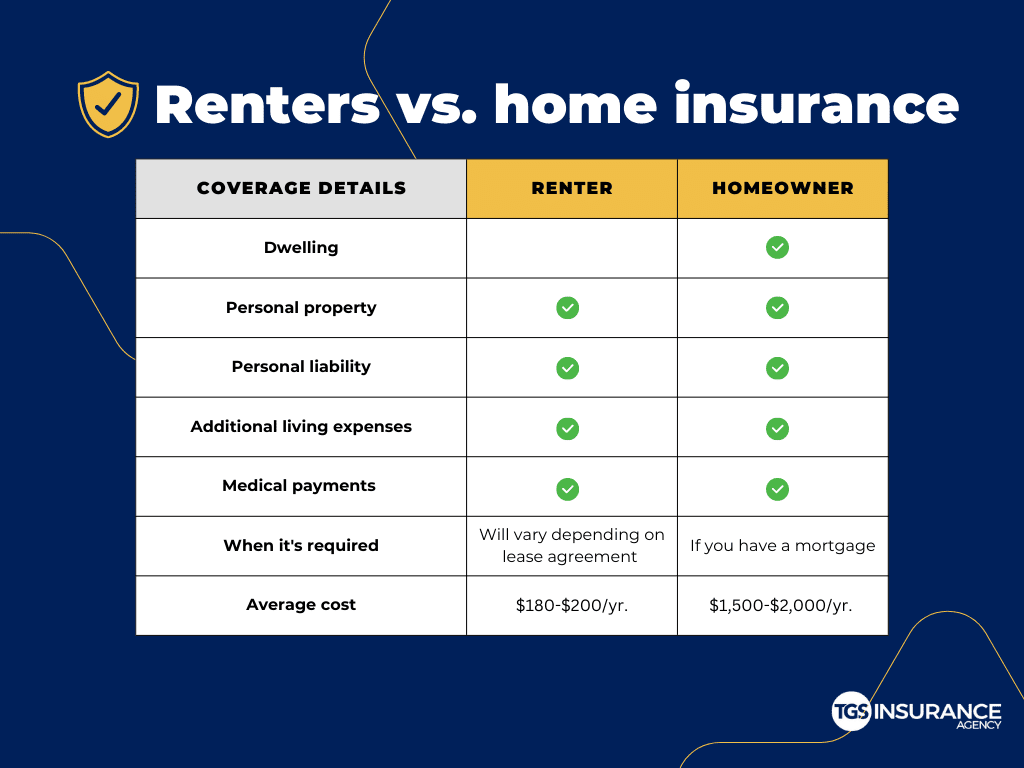
Here’s the kicker: it’s crazy cheap. We’re talking less than a latte a day. Seriously, I’ve seen policies for the price of two avocado toasts. For that, you get protection for your belongings, liability if someone takes a tumble in your hallway, and even extra living expenses if you need to crash at a hotel while your place gets fixed. It’s like having a superhero wallet—without the cape. (Okay, maybe a tiny cape.)
Must Read
A quick tip: when you’re shopping around, don’t just grab the first quote. Ask about “actual cash value” versus “replacement cost.” The first one pays you what your sofa is worth now (depressed and saggy); the second buys you a new one. Go for replacement cost—your sofa deserves a second chance. And bundle it with your car insurance if you can; it’s like a cheat code for savings.
So go ahead, pour that fancy coffee, stroke your monstera, and picture this: you’re safe, your stuff is safe, and your wallet still has money for tacos. That is a lifestyle win. Now go rent that insurance—and maybe treat yourself to a throw pillow that says “I’m covered.” You’ve earned it.