Statement Of Cost Of Sales

There is an underappreciated satisfaction in truly understanding where your money goes, especially when you run a business or manage a household budget. The Statement of Cost...

There is an underappreciated satisfaction in truly understanding where your money goes, especially when you run a business or manage a household budget. The Statement of Cost of Sales is the financial tool that brings this clarity, turning the fog of expenses into a transparent roadmap. People value it because it reveals the direct link between effort and reward, offering a sense of control over financial outcomes.
At its core, this statement calculates the direct costs involved in producing or acquiring the goods you sell. Its key purpose is to separate these costs—like raw materials, labor, and shipping—from indirect expenses, such as rent or marketing. This distinction is crucial because it shows you exactly how much it costs to create one unit of value, before you factor in overhead.
The benefits for everyday life are surprisingly practical. Imagine you run a small bakery: the cost of flour, eggs, and packaging for a batch of cookies appears here, but not your electric bill. By tracking this statement, you can see if your cookie price truly covers your ingredients. If costs rise, you can adjust your recipe or pricing before your margins vanish. This prevents the common disappointment of high sales but negative profit.
Must Read
Consider a freelance graphic designer. The Statement of Cost of Sales would include software subscriptions, contractor fees, and printing costs for client projects. Analyzing it might reveal that a certain type of project—say, logo design—has a much lower cost-to-revenue ratio than full brand packages. This insight allows you to focus your energy on the most profitable work, directly improving your income and work-life balance.
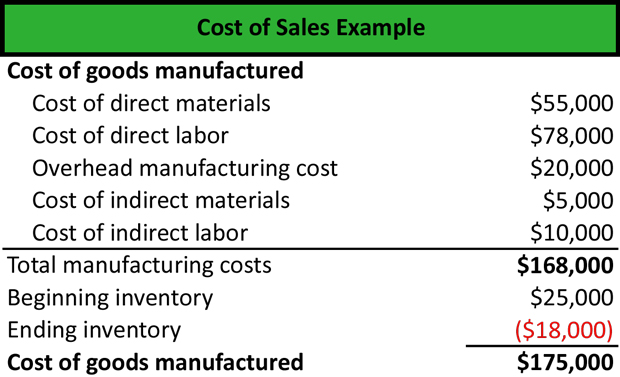 What is Cost of Sales? - Definition | Meaning | Example
To explore it on your own, start by listing every cost that directly touches your product or service. For a lemonade stand, that’s lemons, sugar, cups, and ice—not the table or signs. Next, track your beginning inventory, add any purchases, then subtract ending inventory. That simple formula—Beginning Inventory + Purchases – Ending Inventory—gives you your Cost of Sales.
A few simple tips: use a spreadsheet or a free accounting app to record these costs immediately after each purchase. Separate direct from indirect costs in different columns, and review the statement monthly. Over time, you will spot seasonal trends—like higher ingredient costs in summer—and plan smarter. Mastering this statement turns guesswork into empowerment, making every financial decision more intentional and rewarding.

