Student Loan Grace Period

There’s something genuinely heartening about a pause button in adult life, and few are as practical as the student loan grace period. It’s that sweet, post-graduation window—t...
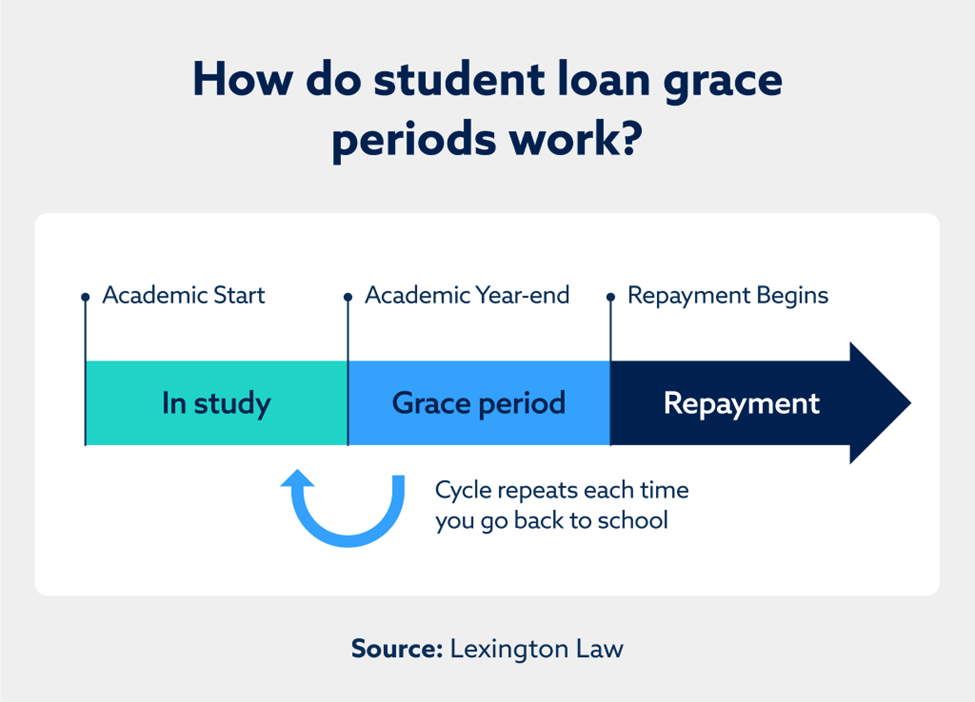
There’s something genuinely heartening about a pause button in adult life, and few are as practical as the student loan grace period. It’s that sweet, post-graduation window—typically six months—where you aren't required to make payments on your federal loans. For recent grads, it’s less a bureaucratic detail and more a breathing room to land on their feet.
The main purpose of this period is simple: transition. You’ve just swapped textbooks for job applications, and a full loan payment on day one would be crushing. This grace period lets you find a job, relocate to a new city, or even start a first business without the immediate pressure of a monthly bill. It benefits not only the graduate but also their co-signers, who get a buffer before payments kick in.
Not all loans are created equal. For Subsidized Direct Loans, the government actually pays the interest during the grace period—a quiet bonus that saves you money. For Unsubsidized loans, interest accrues, so the loan grows slightly. Private loans vary wildly; some offer zero grace period. Check your lender’s fine print, because knowing your type dictates your strategy.
Must Read
A common mistake? Treating the grace period as a total vacation. While you don’t have to pay, you can choose to make voluntary payments on unsubsidized loans to stop interest from piling up. Even paying just the interest each month keeps your loan balance from inflating, giving you a huge advantage when the bill arrives.
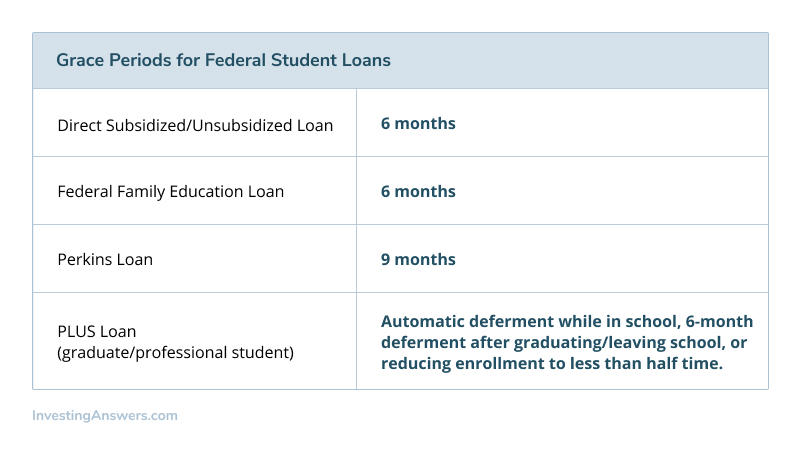 Your Guide to Student Loans | InvestingAnswers
Here are a few actionable tips: First, read your loan servicer’s letters immediately—they announce when your grace ends. Second, use this time to build a budget that includes your future payment. Third, automate your first payment by setting a calendar reminder two months before the deadline. This prevents shock and late fees.
Perhaps the best part is the psychological relief. The grace period is a low-stakes opportunity to experiment: try paying a little extra, or test a repayment plan online. It’s a practical gift from the system—use it to plan, not to panick. When the official payments start, you’ll be ready.

