Tsp C Fund S&p 500 Index

Alright, grab your coffee and pull up a chair. We need to talk about your retirement money—specifically, the TSP C Fund, which is basically the government’s way of saying, “He...
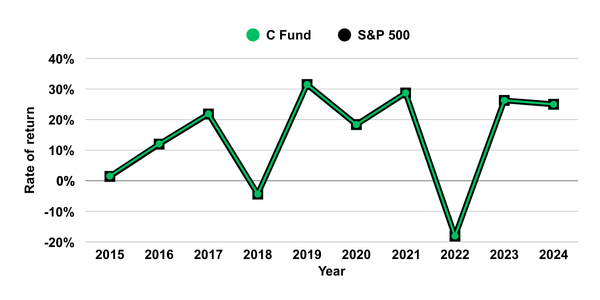
Alright, grab your coffee and pull up a chair. We need to talk about your retirement money—specifically, the TSP C Fund, which is basically the government’s way of saying, “Hey, let’s just bet on America.”
This fund doesn’t mess around with weird micro-stocks or crypto moon-shots. Nope. It simply tracks the S&P 500 index, which is like the A-list guest list of the 500 biggest publicly traded U.S. companies.
What Is the C Fund, Really?
Think of the C Fund as a giant, boring, magical basket. It holds a slice of Apple, Microsoft, Amazon, and about 497 other heavy hitters that power everything from your iPhone to your dentist’s X-ray machine.
Must Read
The “C” stands for Common Stock, which sounds thrilling, right? It’s not. But boring is actually a superpower when you’re trying to retire before you collect Social Security in a hovercraft.
The S&P 500: America’s Scoreboard
The S&P 500 is the index that investors obsess over. It’s the scoreboard that tells you if the U.S. economy is having a good hair day or got caught in a rainstorm.
Fun fact: Since its inception in 1957, the S&P 500 has delivered an average annual return of about 10%. That’s not a typo. Even with crashes, recessions, and that one time we all panic-bought toilet paper, it still marches upward.
Here’s the surprise: If you invested $1,000 in the C Fund in 1988 and left it alone, you’d have over $60,000 today. No stock picking, no late-night trading, just pure, lazy patience.
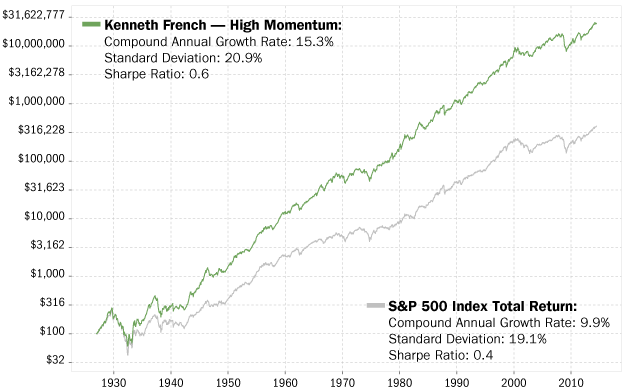 About the TSP Folio Investment Strategy
But Isn’t the C Fund Risky?
Yes, like a roller coaster made of money. It can drop 30% in a bad year—and it has. In 2008, it lost nearly 37%. Ouch. That’s the risk you take for those sweet, sweet gains.
But here’s the kicker: the S&P 500 has recovered from every single crash in history. It’s like that friend who keeps showing up to the party even after embarrassing themselves in 2000, 2008, and 2020.
If you’re within 10 years of retirement, you might want to mix in some safe stuff (like the G Fund). But for young savers? Go all in on the C Fund and forget your password for 20 years.
The Secret Sauce: Low Fees
You know what’s fun? Paying someone 1.5% of your money to manage it. That’s like giving your bartender a $15 tip on a $10 beer. The C Fund laughs at that. Its expense ratio is a microscopic 0.048%.
That means for every $10,000 you have, you pay about $4.80 per year. Compare that to many mutual funds that charge $100+ for the same thing. The C Fund is the budget airline of investing—except you actually arrive richer.
 2 Reasons Why the S Fund Has Been Underperforming the C Fund
A Fun, Slightly Terrifying Fact
The S&P 500 contains companies that didn’t even exist 30 years ago—like Google, Tesla, and Nvidia. The index automatically kicks out losers and adds winners. It’s like a reality TV show where the weakest stock gets voted off, and the champion gets a bigger slice of your retirement.
So when you buy the C Fund, you’re not just buying today’s giants. You’re buying tomorrow’s creepy AI overlords and robot vacuum empires. Relax, it’s fine.
The Bottom Line (With a Joke)
The TSP C Fund is the lazy genius of retirement investing. You don’t have to research companies or watch CNBC while eating cereal. Just set it, forget it, and let the American economy do the heavy lifting.
And if it crashes? Don’t panic. Buy more. Then go for a walk. The S&P 500 has a 100% success rate of coming back—like a bad ex who always brings pizza.
Now go log into your TSP account and give the C Fund a high-five. Your future self will thank you, probably from a beach in Florida, sipping something with a tiny umbrella.
