Using Va Loan For Investment Property

Alright, let’s talk about a secret weapon. You know that VA Loan you earned? The one with zero down payment and no mortgage insurance? Yeah, that one. Here’s the wild part: Ev...
Alright, let’s talk about a secret weapon. You know that VA Loan you earned? The one with zero down payment and no mortgage insurance? Yeah, that one.
Here’s the wild part: Everyone thinks it’s only for your primary home. But with a little cleverness, you can use it for investment property. Seriously. It’s like finding out your Swiss Army knife also makes coffee.
The "Live There First" Loophole
You can’t just buy a rental with a VA Loan and never step foot inside. The rule is simple: you must occupy the property as your primary residence for at least 12 months. That’s it.
Must Read
After a year, you can move out and convert it into a rental. Boom. Now you’re a landlord without a massive down payment. It’s the slow-burn strategy—like marinating a steak for perfect flavor.
The Multi-Unit Magic Trick
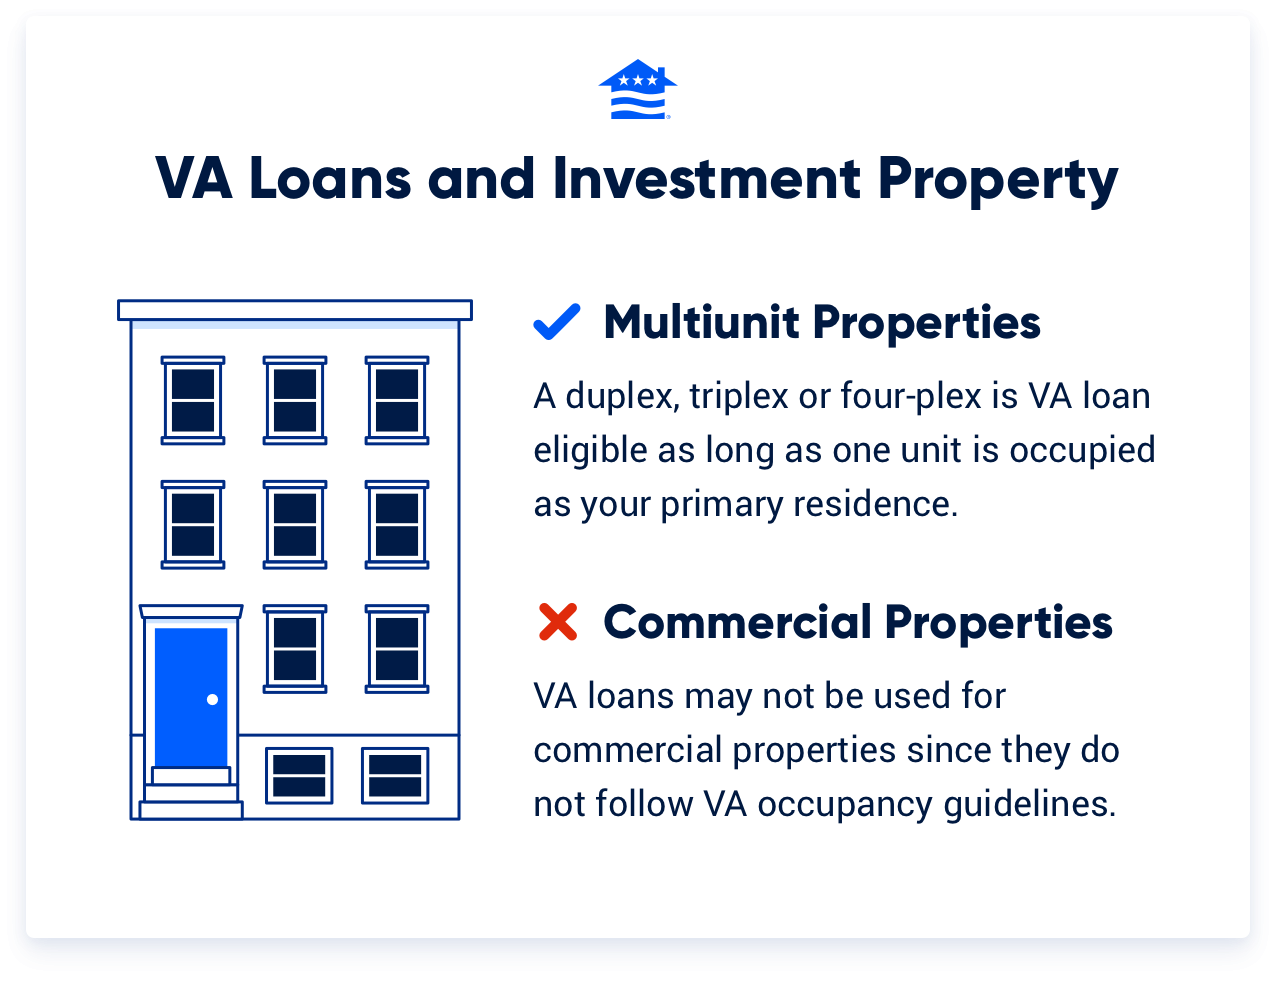
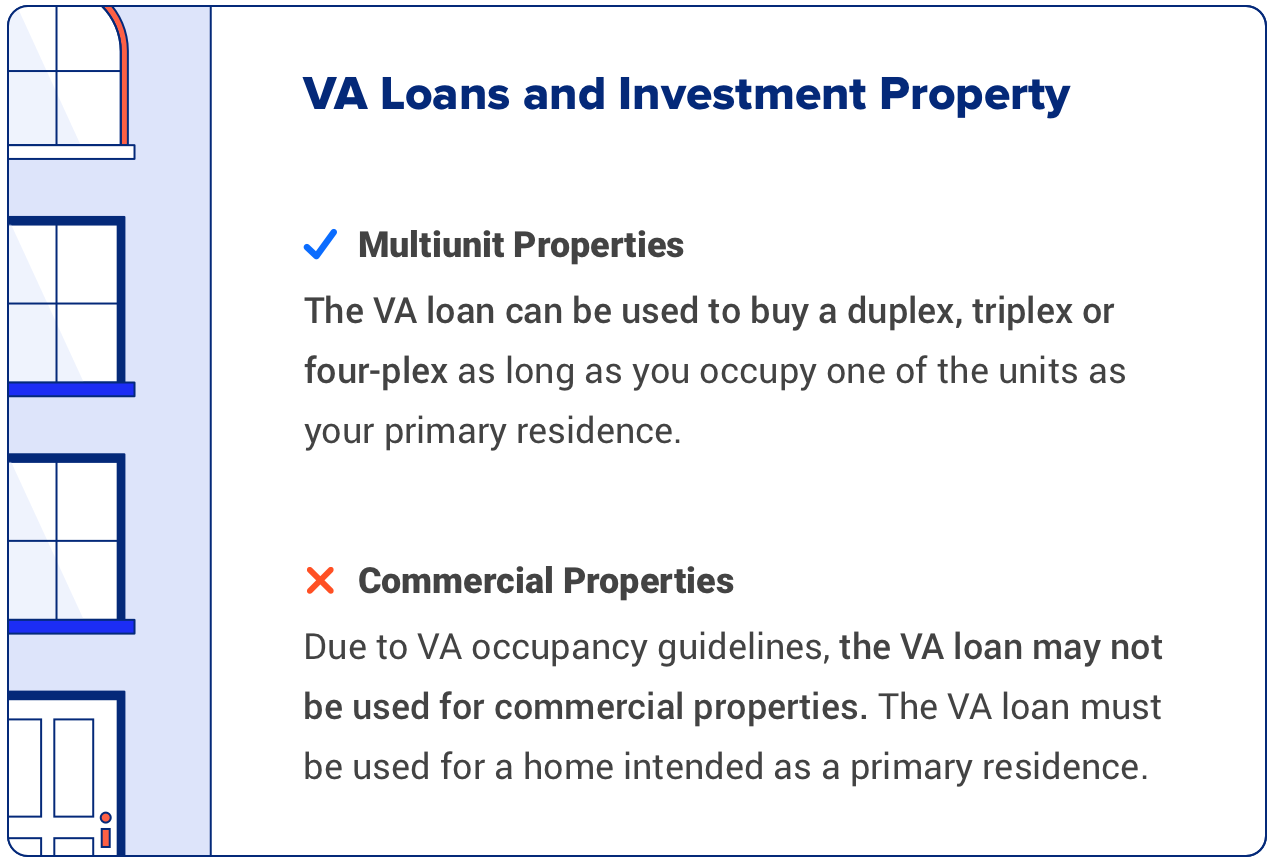
Here’s where it gets fun. Buy a duplex, triplex, or fourplex with your VA Loan. Live in one unit. Rent out the other three. Your tenants literally pay your mortgage while you sip coffee in your living room.
Quirky fact: The VA doesn’t care how many units you buy—up to four. That’s like ordering a pizza and getting three free slices because you ate one first. Insanity, right?
 How To Use The VA Loan To Invest In Real Estate - YouTube
The "Second Tier" Entitlement Surprise
Think you can only do this once? Nope. You have second-tier entitlement. Meaning, if you sell your first property or pay off the loan, you can reuse your VA benefit for another investment property.
This is the financial equivalent of a video game extra life. You can chain them together. Buy, live, rent, repeat. Your future self will high-five you.
The Catch (Because There’s Always One)
Of course, it’s not all rainbows and tenants who pay on time. The big rule: you must move in within 60 days of closing. And you can’t just “claim” you live there. The VA checks on you—like a friendly but nosy neighbor.
Also, if you already have a VA Loan on another home, your residual income and debt ratios get tight. It’s like trying to fit a giant pumpkin into a small car. Doable, but you need a calculator.
 Can You Use Va Loan For Investment Property? - Get Money Saving
Why This Is Just Fun
This topic is a party trick for real estate geeks. Imagine telling your buddies: “Yeah, I bought a fourplex with $0 down.” Their jaws drop. You look like a genius.
Plus, the interest rates are usually lower than conventional loans. That’s like getting a discount on a Ferrari. It’s unfair, but you earned it. Serve your country, get a deal.
So here’s the punchline: Your VA Loan is a lazy investment tool—if you know how to use it. It doesn’t require huge cash. It doesn’t punish you for leaving after a year. It just asks you to live in your investment for twelve months. That’s it.
Now go call a lender who actually understands VA Loans. Not all of them do. Find one who smiles when you say “multi-unit.” That’s your person. Go build your rental empire. One year at a time.
