Va Loan For Investment Property

Let’s be honest: buying a house is a lot like assembling flat-pack furniture. It sounds exciting, but halfway through, you’re knee-deep in confusing rules and wondering if you...
Let’s be honest: buying a house is a lot like assembling flat-pack furniture. It sounds exciting, but halfway through, you’re knee-deep in confusing rules and wondering if you’ll ever get that shelf upright. For veterans, active-duty members, and military families, the VA loan is like finding that missing screwdriver. It makes things smoother, but there’s a big myth floating around: that you can only use it for your personal home.
The Big Secret: Can You Use a VA Loan for an Investment Property?
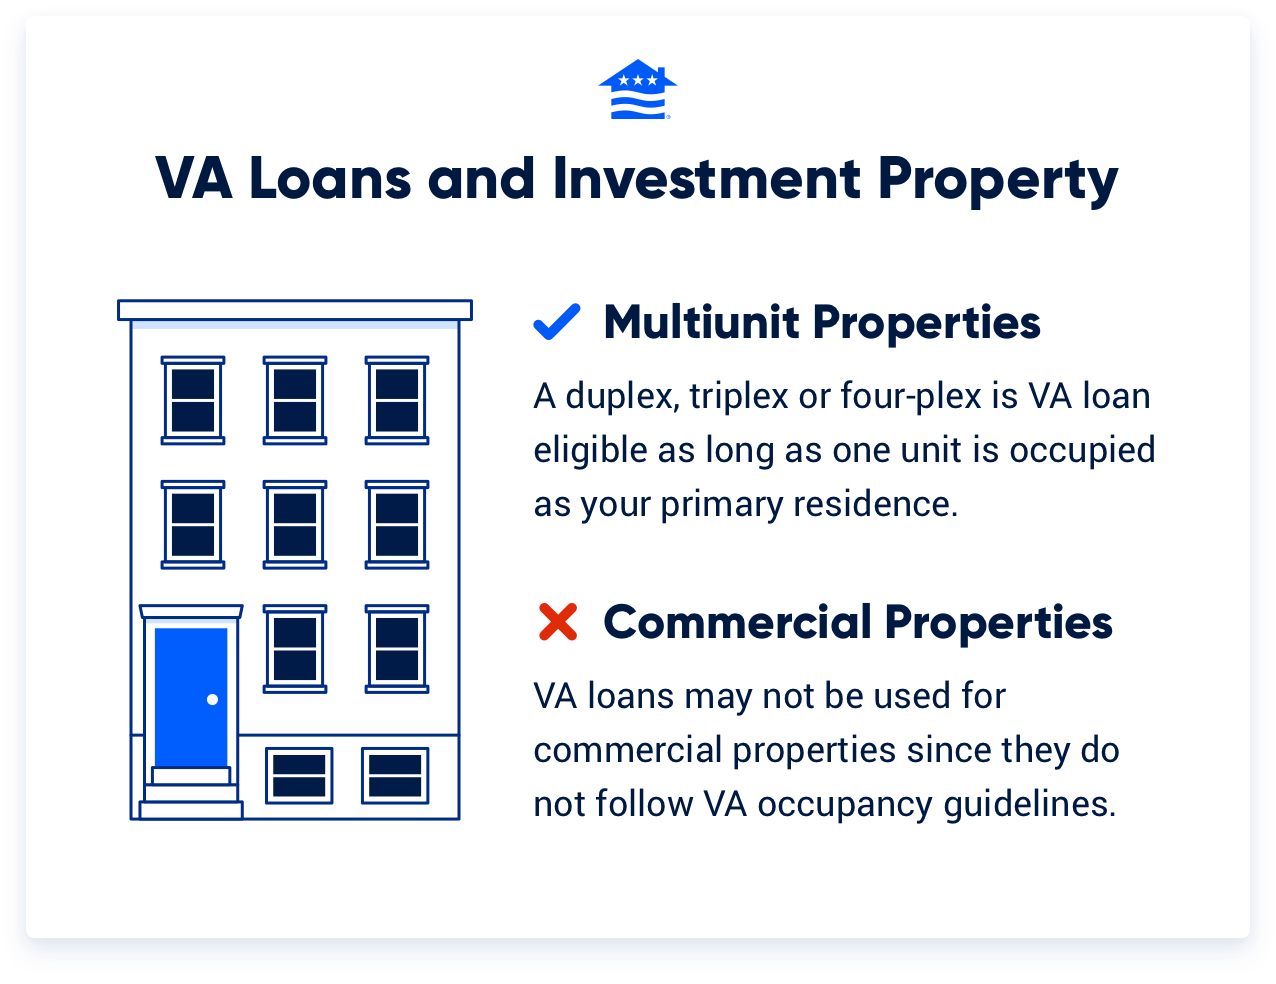
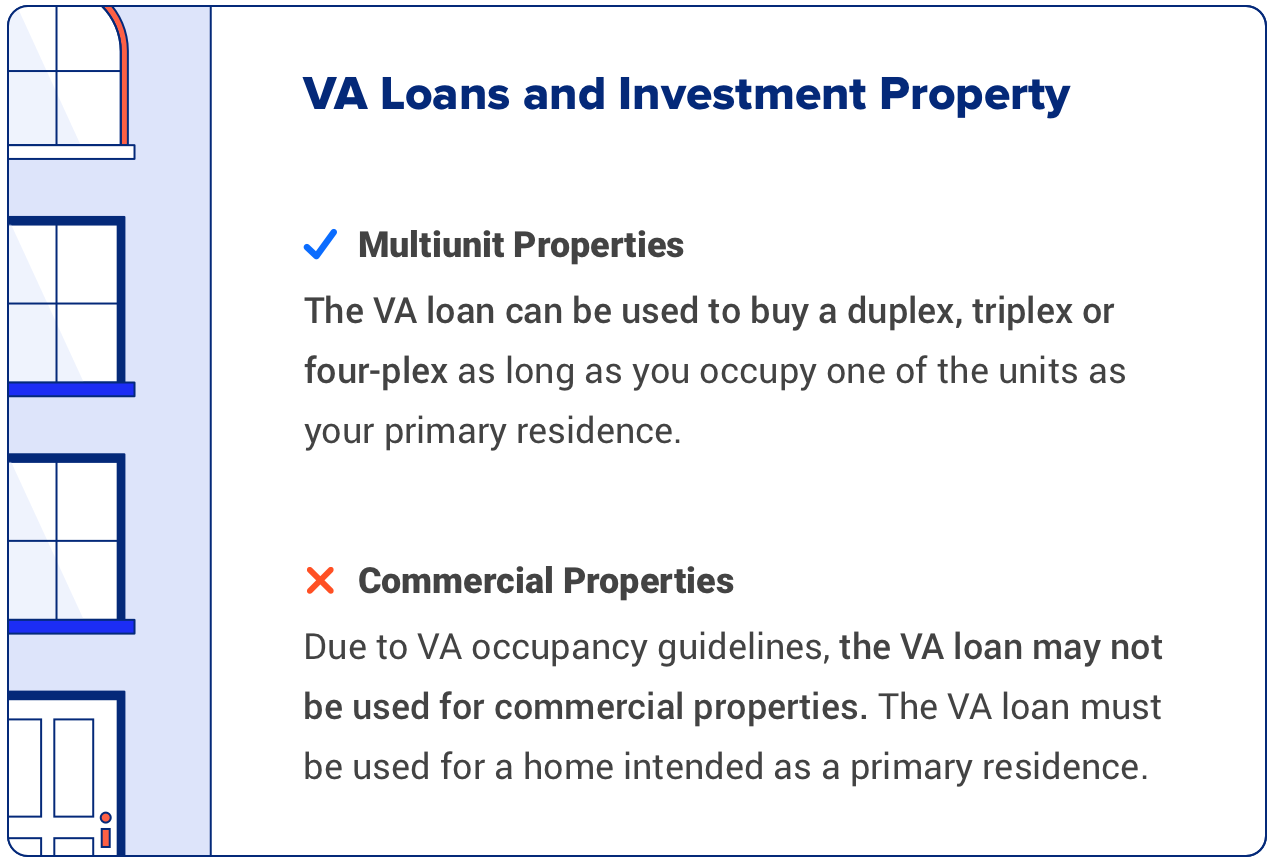
Technically, the official rules say no. The VA loan is designed for owner-occupied homes, meaning you have to live there. But here’s where everyday life gets clever. Think of it like this: you want to buy a duplex, live in one side, and rent out the other. That’s not just allowed; it’s a fantastic strategy. The VA calls this “investment” because you’re collecting rent, but the rule is satisfied because you’re the guy making coffee in the kitchen next door.
Imagine you buy a triplex. You live in Unit A, and your tenants in Units B and C pay your mortgage. That’s pure smart living. The VA loan requires you to move in within 60 days, but after a year, you can move out and rent your own unit, too. You’ve just turned a personal loan into an investment property without a second mortgage.
Must Read
Why This Matters for Your Morning Coffee
Let’s put a face on this. Meet Sarah, a Navy veteran. She bought a four-plex with her VA loan, lives in the smallest unit, and the rent from the other three covers her entire mortgage plus her electric bill. She still buys fancy oat milk lattes every morning. That’s financial freedom disguised as a loan. You don’t need a 20% down payment, and there’s no private mortgage insurance (PMI) eating your savings.
Now compare that to your buddy Dave, who bought a normal house. Dave is still paying PMI, and his monthly payment makes him wince. Meanwhile, Sarah’s tenants are paying her way. The VA loan turns your living situation into a money-making machine from day one.
 Hack Your VA Loan & Use it for Investment Property—Here's How
The Clever Workaround: The “Two-Year Rule”
Here’s a little story dads love to tell at barbecues. You buy a single-family home with a VA loan, live there for two years, then your job moves you to another state. You don’t have to sell. You can rent out that first house and buy another VA loan home at your new location. Suddenly, you own two houses: one is a rental investment, one is where you sleep. The rule allows this because you genuinely lived there first.
It’s like having a spare key. You’re not breaking any rules; you’re just using the system’s flexibility. This is how everyday people build wealth without a giant pile of cash. You just need patience and a willingness to be a landlord for a while.
 Can You Use Va Loan For Investment Property? - Get Money Saving
The Fine Print (But It’s Still Fun)
You cannot buy a vacation home or a pure fix-and-flip with a VA loan. You must intend to move in. But if you buy a four-unit building and live in one, you’re golden. The Department of Veterans Affairs cares about your intent, not your profit.
So why should you care? Because life is expensive, and your military service earned you a tool that works in the real world. You don’t need a real estate guru’s course. You just need a home with an extra door that someone else pays for. That’s not cheating; that’s smart life design. And yes, you can still have that oat milk latte while your tenants cover the bills.
