Voluntary Surrender Car

Let’s be honest: we’ve all had that one car that felt less like a vehicle and more like a financial black hole with a steering wheel. You know the one. It makes a sound like a...
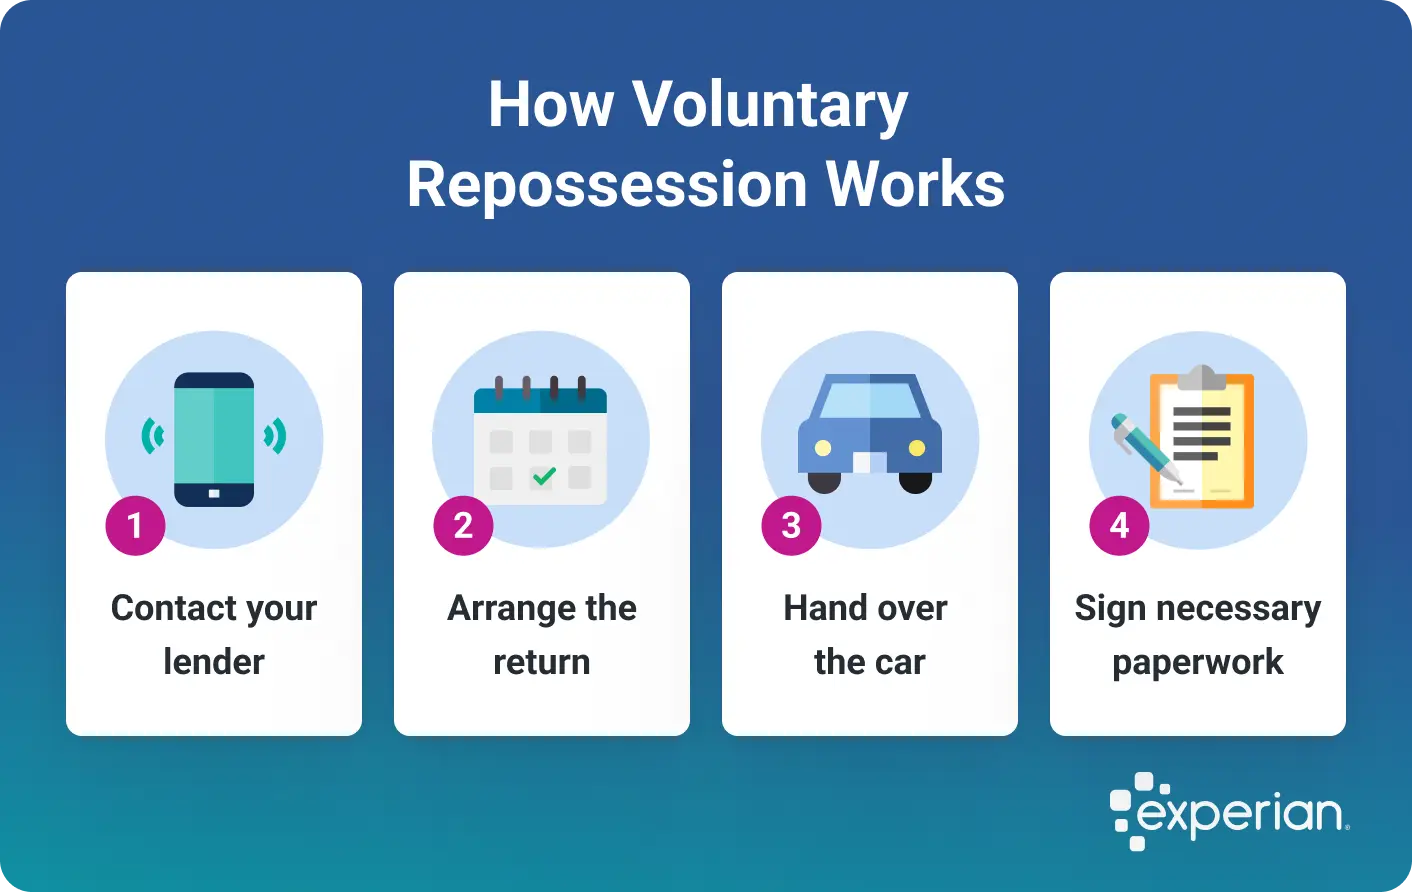
Let’s be honest: we’ve all had that one car that felt less like a vehicle and more like a financial black hole with a steering wheel. You know the one. It makes a sound like a dying whale every time you turn left, and the check engine light has become your car’s permanent mood ring. Before you contemplate pushing it off a cliff for the insurance money, there’s a secret escape hatch: the Voluntary Surrender Car.
Think of it as the automotive equivalent of tapping out in a wrestling match. You walk up to your lender, hand over the keys, and say, “I quit. You win. She’s all yours.” It’s not glamorous—there’s no marching band, no trophy—but it’s a legal, real-world way to get out of a loan you can’t afford. You basically return your car like it’s a pair of shoes that don’t fit, except the shoes cost $30,000 and depreciated the second you drove off the lot.
The Shocking Truth: Your Credit Will Cry (But Not As Hard As You Think)
Here’s the surprising fact that most people don’t know: a voluntary surrender is almost identical to a repossession on your credit report. That’s right—the bank doesn’t care if you drove it there gently or they came with a tow truck in the dead of night. Both hit your credit score like a punch from a boxing kangaroo. The benefit? You avoid the drama of finding your car missing from the driveway, which is a plus for your blood pressure and your pride.
Must Read
But here’s the kicker: you also avoid a lot of nasty fees. When they repossess a car, they charge you for towing, storage, and a “we had to look at it” fee. By surrendering it yourself, you skip the storage fees and reduce the chance of them selling your car at auction for peanuts and suing you for the rest. It’s like choosing to clean your own apartment before the landlord evicts you—you still leave, but with slightly more dignity.
The “Oops, I Still Owe Money” (The Deficiency Judgement)
Now for the part they don’t put on the brochure: the deficiency balance. Picture this: you owe $15,000 on your beloved sedan. The bank sells it at auction for $8,000 on a rainy Tuesday. You’re still on the hook for the remaining $7,000, plus a bunch of fees they call “reasonable costs.” It’s like breaking up with a restaurant, and then they send you a bill for the leftovers you didn’t eat. Fun, right?
 What is Voluntary Repossession and How It Works
Some states protect you from this. In California, for example, they can’t come after you for the difference on car loans under certain conditions. But in others, the bank will hunt you down like you stole their last donut. Always check your local laws, or you might end up paying for a car you no longer own—which is the definition of a bad magic trick.
Is It Ever a Good Idea? (Spoiler: Yes, Sometimes)
Okay, so when should you actually pull the trigger on a voluntary surrender? If your car is worth half of what you owe and you can’t make payments, it’s often smarter than starving yourself to pay for a Honda Civic. It’s also a lifesaver if you’ve already wrecked your credit and need to stop the bleeding. Think of it as a tactical retreat in the war of personal finance.
 Voluntary Repossession: Pros, Cons, and What to Do Instead
Just remember: this is a last resort, not a first date idea. Try selling the car yourself first. If that fails, call your lender and beg for a deferment. But if all else fails? Park it nicely, wipe down the cup holders, and hand over the keys with a sad smile. You might not feel like a winner, but at least you won’t be pushing that whale off a cliff.
And hey, the bus isn’t that bad. You can read, you can nap, and nobody asks you to pay for a mysterious “administrative fee” every month. Silver linings, my friend.
