What Is The C Fund In Tsp

So, you’ve got a Thrift Savings Plan, or TSP—a fancy name for your government retirement piggy bank. And inside that piggy bank, there’s a fund with a simple name: the C Fund....
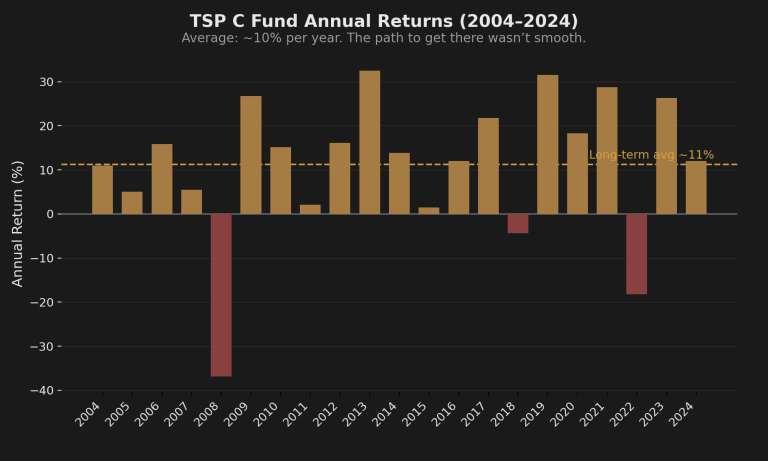
So, you’ve got a Thrift Savings Plan, or TSP—a fancy name for your government retirement piggy bank. And inside that piggy bank, there’s a fund with a simple name: the C Fund. But what is it, really? Imagine you’re at a potluck, and the C Fund is that one famous dish everyone talks about—big, bold, and a little unpredictable, but it’s usually the life of the party.
The C Fund in a Nutshell
The C Fund stands for the Common Stock Index Fund—basically, it’s a slice of the entire U.S. stock market. Think of it as buying a tiny piece of 500 of America’s biggest companies, like Apple, Microsoft, and Disney. It’s not a secret club; it’s just a way to let your money grow alongside the giants of the economy.
Here’s the emotional part: the C Fund is the thrill-seeker of the TSP family. On good days, it feels like finding a $20 bill in your winter coat. On bad days, it’s like stepping on a LEGO—painful, but you’ll walk it off. The key is to stay calm and remember that over the long haul, this fund has a history of climbing higher.
Must Read
Why Should You Care?
Because your future self is counting on you. Picture you at age 67, kicking back on a porch with a cup of coffee and no financial stress. The C Fund is the engine that can help get you there, if you treat it right. It’s not a get-rich-quick scheme—it’s a slow-cooker recipe for wealth.
Let’s use a real-life comparison. Say your TSP is your monthly pizza budget. The G Fund (government bonds) is the plain cheese—safe, reliable, but boring. The C Fund is the pepperoni and extra cheese—more flavor, more risk, but way more satisfying over time. You don’t skip dinner because the pepperoni is risky; you trust it because it’s worked for decades.
 Market Jitters Hit TSP Returns In December—What Matters For The Full
How It Works (Without the Jargon)
The C Fund tracks the S&P 500 Index, which is just a list of America’s top 500 public companies. When these companies make money, the fund’s value goes up. When they hit a rough patch, it goes down. Think of it like your favorite sports team: they don’t win every game, but over a season, they usually come out ahead.
Here’s a little story. My buddy Dave put 20% of his TSP into the C Fund back in 2010. He watched it dip in 2020 during the pandemic and almost panicked. But he kept it there, and by 2024, his account had more than doubled. He didn’t do anything special—he just stayed patient.
The Fun Part: It’s Simple
You don’t need to be a stock market whiz. The C Fund is a set-and-forget kind of deal. No checking the news every morning, no screaming at your computer. You just pick a percentage (like 40% or 60% of your TSP) and let time do the heavy lifting.
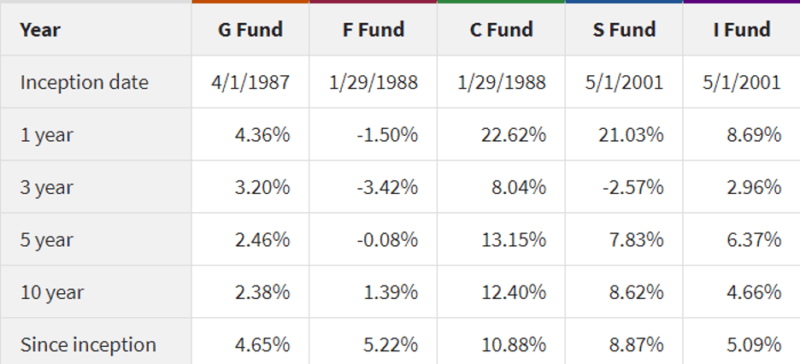 Is 100 Percent in the C Fund a Good Idea?
And here’s the best part: you’re not gambling—you’re investing in America’s economic engine. Every time someone buys a new iPhone or orders from Amazon, your C Fund gets a tiny boost. It’s like having a thousand part-time jobs all working for your retirement.
A Gentle Reminder
The C Fund isn’t for everyone—if you’re ten years from retiring, you might want less of it. But for most of us with decades to go, it’s the secret sauce that turns a modest paycheck into a comfortable future. Start small, think big, and don’t let short-term jitters steal your long-term dreams.
So go ahead, give the C Fund a little love in your next TSP allocation. Your future porch-sitting self will thank you with a smile and a warm cup of coffee.
