What's The Difference Between Basic And Supplemental Life Insurance

Let’s be real: life insurance sounds about as exciting as watching paint dry. But stick with me, because this is actually a story about you, your coffee fund, and that time yo...

Let’s be real: life insurance sounds about as exciting as watching paint dry. But stick with me, because this is actually a story about you, your coffee fund, and that time you panic-bought a fancy blender. We’re talking about basic versus supplemental life insurance, and I promise it’s less confusing than your phone’s settings menu.
Think of basic life insurance as the free slice of pizza at a work party. It’s there. It’s decent. But it’s usually just one slice—and not the one with pepperoni. Your employer likely offers it as a perk, covering about one or two times your annual salary. It’s a safety net, sure, but it’s more like a hammock than a fortress.
Now, supplemental life insurance is the extra-large, stuffed-crust, “I’ll take the leftovers home” pizza you order yourself. You pay for it, but you get way more coverage. It fills the gap between what your basic policy pays and what your family would actually need to keep living their lives—like paying the mortgage or sending your kid to that overpriced summer camp.
Must Read
Here’s the thing: basic insurance is cheap (often free), but it’s tied to your job. Lose your job, lose the pizza. If you get laid off or switch companies, poof—your coverage vanishes. That’s when supplemental insurance saves the day. You own it personally, so it follows you like your favorite pair of sweatpants.
Why should you care right now?
Imagine your best friend suddenly has to pay for a funeral, a car loan, and your massive collection of coffee mugs. With basic insurance alone, they might get a check for $50,000—which sounds big until you realize a year of rent eats half of it. Supplemental insurance can turn that into $300,000 or more, meaning your friend can actually grieve without also worrying about eviction.
 Basic Group Life Insurance Supplemental Life Insurance Group
Let me tell you about Jen. Jen had basic life insurance from her job—$20,000. She thought, “Eh, good enough.” Then she bought a house and a puppy. Whoops. Her mortgage alone was $180,000. If she’d passed away, her family would be selling that dog on Craigslist to cover the bills. She added a $250,000 supplemental policy for the cost of two takeout dinners a month. Now she sleeps like a baby.
The sweet spot? Most people stack them. Keep your basic policy (free money!), then add supplemental coverage to cover the real needs: kids’ college, debt, or that dream kitchen remodel. You don’t need to be a millionaire—just someone who doesn’t want their family to eat ramen forever.
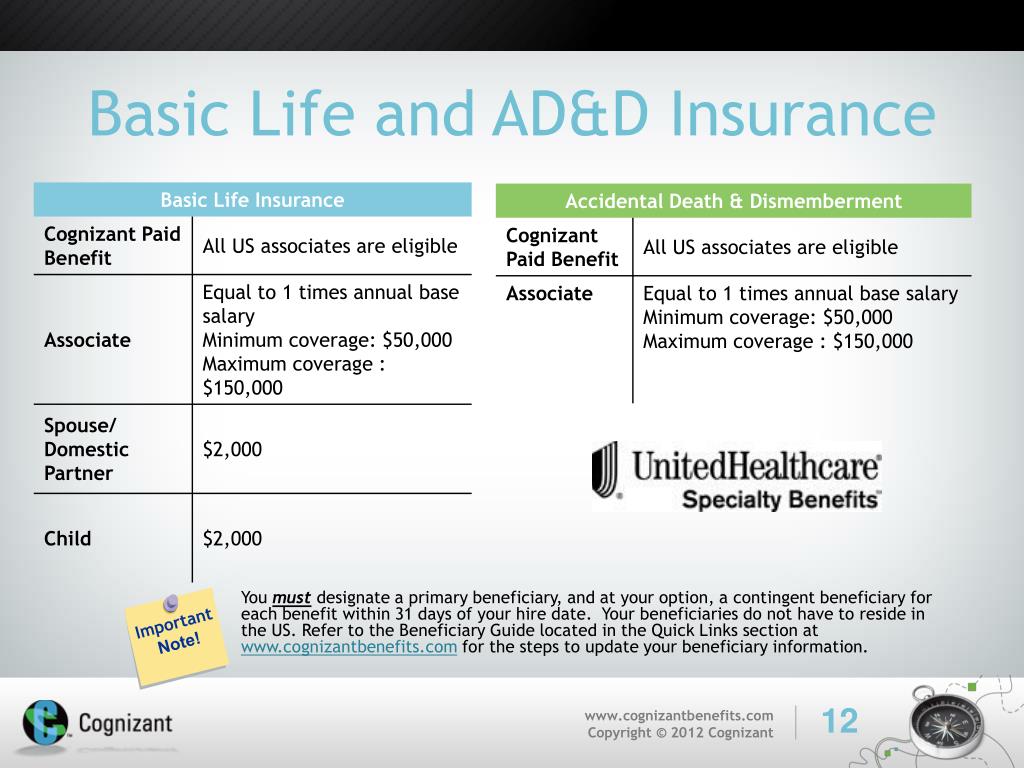 PPT - 2013 Benefits Orientation PowerPoint Presentation, free download
One more thing: you can get supplemental insurance through work (often with a discount) or buy it on your own. If you’re young and healthy, it’s stupid cheap. Like, less than your Netflix subscription cheap. That’s a steal for peace of mind.
So here’s the takeaway: basic life insurance is a start, like a single sock. Supplemental insurance is the matching pair. Together, they keep your loved ones warm, protected, and laughing—not panicking over bills. Now go check your benefits package. Your future self (and your family) will thank you.
